23 October 2026 | Income Tax Updates | Foreign Assets & International Taxation | Foreign Property Income Tax Notice
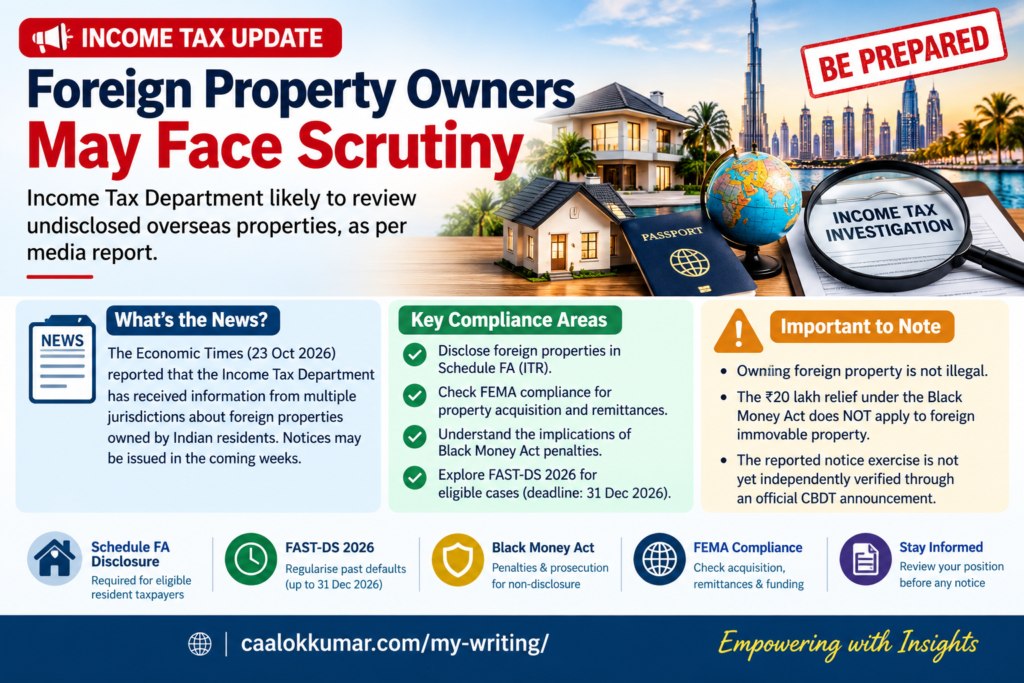
Foreign Property Income Tax Notice 2026: Indian residents holding overseas properties may soon face increased scrutiny from the Income Tax Department. According to a report published by The Economic Times on 23 October 2026, tax authorities have reportedly received information concerning foreign immovable properties owned by Indian residents from multiple jurisdictions.
The development comes at a significant time, as the Foreign Assets of Small Taxpayers Disclosure Scheme (FAST-DS 2026) remains open until 31 December 2026.
For taxpayers who own residential apartments, commercial premises, land or other immovable properties outside India, the immediate question is whether such assets were properly disclosed in their Indian income-tax returns and whether the source of investment can be satisfactorily explained.
Importantly, owning property abroad is not itself illegal. The tax consequences depend upon the taxpayer’s residential status, how the property was acquired, the source of funding and compliance with applicable Indian tax and foreign exchange regulations.
Income Tax Department May Issue Notices for Undisclosed Foreign Properties
According to The Economic Times, an official associated with the investigation division of the Income Tax Department reportedly indicated during a webinar attended by tax professionals and auditors that notices relating to undisclosed overseas property holdings could be issued in the coming weeks.
The report suggests that information concerning Indian residents’ overseas properties has been received through international information-sharing arrangements, including spontaneous exchange of information and other sources.
The development is particularly relevant for individuals owning properties in overseas jurisdictions, including popular investment destinations such as Dubai.
However, the reported proposal should not be confused with an officially notified nationwide enforcement programme. The precise scope, number of taxpayers involved and jurisdictions covered have not been publicly confirmed through a specific CBDT notification identified as of 23 October 2026.
The broader regulatory message is nevertheless clear: foreign property ownership and corresponding disclosures are increasingly capable of being examined using information received from overseas authorities.
How Can the Income Tax Department Obtain Information About Foreign Properties?
India participates in international tax information-exchange arrangements that allow tax authorities to obtain information concerning overseas income, assets and financial transactions.
Three important mechanisms are:
1. Automatic Exchange of Information (AEOI)
Under international arrangements such as the Common Reporting Standard (CRS), participating jurisdictions exchange specified information concerning reportable financial accounts.
Such information may include overseas bank accounts, custodial accounts and certain investment holdings.
However, CRS-based automatic reporting should not be confused with a universal international property-ownership database. Direct ownership details of land and buildings are not automatically exchanged merely because a country participates in CRS.
2. Spontaneous Exchange of Information
Under applicable tax treaties and information-exchange arrangements, a foreign tax authority may proactively share information with India where it considers that information relevant to Indian taxation.
For example, information concerning an overseas property transaction may be shared if the foreign authority identifies circumstances suggesting potential tax non-compliance involving an Indian resident.
This mechanism is particularly relevant to the latest reported development.
3. Exchange of Information on Request
Indian tax authorities may also seek specific information from foreign jurisdictions during investigations, assessments or other authorised proceedings.
Such requests may concern property ownership, related financial transactions, beneficial ownership or the source of funds, subject to the applicable legal framework.
Consequently, taxpayers should not assume that overseas immovable properties remain beyond the reach of Indian tax authorities simply because those properties do not appear in Form 26AS or the Annual Information Statement (AIS).
For related developments, read our article on foreign assets not disclosed in ITR and increased income-tax scrutiny.
Is Foreign Property Required to Be Disclosed in an Indian Income Tax Return?
Yes, where the taxpayer is subject to the applicable foreign-asset reporting requirements.
Under the Income-tax Act, 1961, read with the prescribed income-tax return forms and section 139(1), resident and ordinarily resident individuals are generally required to disclose specified foreign assets in Schedule FA.
The obligation extends to qualifying foreign immovable properties, even where the property:
- Has not generated rental income.
- Was acquired several years earlier.
- Was purchased from income already subjected to tax.
- Was acquired while the person was previously a non-resident.
- Is held jointly with another person, where reporting conditions are satisfied.
For Assessment Year 2026-27, Schedule FA requires reporting of relevant foreign assets held during the calendar year 1 January 2025 to 31 December 2025.
Foreign immovable property is reportable in Table C of Schedule FA, as applicable.
What About NRIs and RNOR Taxpayers?
The distinction between residential categories is crucial.
| Residential status | Schedule FA requirement |
|---|---|
| Resident and Ordinarily Resident (ROR) | Generally applicable |
| Resident but Not Ordinarily Resident (RNOR) | Not required under the normal Schedule FA instructions |
| Non-Resident (NR) | Not required under the normal Schedule FA instructions |
Residential status must be determined separately for each relevant financial year under section 6 of the Income-tax Act, 1961.
Further, the exemption from Schedule FA reporting does not automatically exclude income that is otherwise taxable in India under section 5.
Taxpayers should also note that Schedule FA requirements and eligibility for FAST-DS 2026 are governed by different statutory provisions.
For a detailed explanation of foreign-asset reporting, refer to Foreign Assets in ITR AY 2026-27: Schedule FA, Foreign Income and Foreign Tax Credit.
Foreign Property Purchased From Tax-Paid Income: Is There Still a Problem?
This is one of the most important issues in foreign-property scrutiny.
Consider an Indian resident who legitimately remitted money through an authorised bank under the Liberalised Remittance Scheme (LRS) and purchased a residential apartment overseas.
The purchase was funded from declared income, and the remittance complied with the applicable FEMA requirements.
However, the taxpayer subsequently failed to disclose the apartment in Schedule FA.
In such a case, the foreign property should not automatically be regarded as an asset acquired from unexplained income.
Nevertheless, a failure to report the foreign immovable property can independently create exposure under the Black Money Act, even where the source of investment is explained.
A careful distinction is therefore necessary between:
Non-disclosure of an explained foreign asset: The source of acquisition is identifiable, but the prescribed reporting requirement was not complied with.
Undisclosed foreign income or unexplained investment: Income chargeable to tax in India was omitted, or the source of investment cannot be satisfactorily established.
The legal consequences and available remedies may differ substantially.
Black Money Act: Penalty and Prosecution Risks for Foreign Property
The Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015 contains specific provisions relating to undisclosed foreign income, foreign assets and reporting failures.
The following provisions deserve particular attention.
| Relevant provision | Broad legal implication |
|---|---|
| Section 3 | Charge of tax on undisclosed foreign income and assets |
| Section 4 | Scope of undisclosed foreign income and assets |
| Section 41 | Penalty relating to tax computed under section 10 |
| Section 42 | Penalty for failure to furnish a required return in specified cases |
| Section 43 | Penalty for failure to disclose foreign assets/income or inaccurate reporting |
| Sections 49–50 | Prosecution provisions relating to specified foreign-asset reporting defaults |
Sections 42 and 43 prescribe a penalty of ₹10 lakh for specified defaults, subject to the applicable statutory conditions.
The Act also contains provisions for tax, penalties and prosecution in appropriate cases. These consequences are not automatically attracted merely because an individual owns property overseas.
Important: The ₹20 Lakh Relief Does Not Apply to Foreign Immovable Property
A particularly significant distinction concerns the statutory monetary exclusion for certain foreign assets.
Following the Finance (No. 2) Act, 2024, sections 42 and 43 contain an exclusion for specified foreign assets, other than immovable property, where their aggregate value does not exceed ₹20 lakh.
Budget 2026 also addressed corresponding prosecution provisions.
The Government’s Budget 2026 FAQs clarify that foreign immovable property remains outside the ₹20 lakh relief.
This means that an otherwise reportable overseas property cannot be omitted merely because its value is below ₹20 lakh.
However, any proposed penalty or prosecution must still satisfy the applicable statutory requirements, and the taxpayer’s individual circumstances remain relevant.
FAST-DS 2026: Opportunity to Regularise Undisclosed Foreign Property
The timing of this reported enforcement development is significant because the Government introduced the Foreign Assets of Small Taxpayers Disclosure Scheme, 2026 (FAST-DS).
The scheme is contained in Chapter IV, sections 130 to 144 of the Finance Act, 2026.
It was operationalised through CBDT Notification No. 114/2026 dated 14 August 2026 and became effective from 16 August 2026.
The last date to submit the prescribed declaration is 31 December 2026.
The scheme provides two different routes, depending upon the nature of the foreign asset or income.
Category 1: Undisclosed Foreign Income or Assets up to ₹1 Crore
This category broadly addresses qualifying undisclosed foreign income or foreign assets where the source of investment is unexplained.
The aggregate amount covered by the declaration must not exceed ₹1 crore.
The amount payable broadly comprises:
- Tax at 30%.
- An additional amount equal to 100% of the tax.
Accordingly, the effective combined payment is 60% of the amount determined under the scheme.
Category 2: Explained Foreign Assets up to ₹5 Crore
This category is especially relevant to taxpayers who acquired overseas properties:
- From income earned while they were non-residents and subsequently failed to disclose the assets after becoming resident; or
- From income already offered to tax in India, but omitted the assets from the prescribed return schedule.
Subject to the statutory conditions, aggregate qualifying foreign assets not exceeding ₹5 crore may be disclosed on payment of a fixed fee of ₹1 lakh.
FAST-DS 2026 Comparison
| Particular | Category 1 | Category 2 |
|---|---|---|
| Nature | Qualifying untaxed or undisclosed foreign assets/income | Explained foreign assets with specified reporting defaults |
| Maximum aggregate amount | ₹1 crore | ₹5 crore |
| Payment | Effective 60% | Fixed ₹1 lakh |
| Valuation date | 31 March 2026 | 31 March 2026 |
| Declaration deadline | 31 December 2026 | 31 December 2026 |
Important: Not every overseas property automatically qualifies under FAST-DS. Eligibility depends on the statutory conditions, residential status, source of acquisition, valuation and applicable exclusions.
For detailed conditions, valuation rules and filing procedures, read Foreign Assets Disclosure Scheme 2026: Complete FAST-DS Guide.
How Will Foreign Immovable Property Be Valued Under FAST-DS?
Foreign property valuation can determine whether the taxpayer qualifies under the ₹1 crore or ₹5 crore thresholds.
The FAST-DS Rules prescribe asset-specific valuation methods.
For immovable property, the prescribed methodology broadly requires consideration of acquisition cost and fair market value as at the valuation date, subject to the detailed rules and adjustments.
The valuation date under the scheme is 31 March 2026.
Consequently, taxpayers should not assume that the historical purchase price, outstanding housing loan or a self-estimated current resale value will necessarily represent the correct statutory value.
Where appropriate, independent property valuation, acquisition documents and currency-conversion workings should be obtained.
This is especially important for property acquired several years earlier in overseas markets where prices have subsequently increased.
Can FAST-DS Protect Against Income Tax Notices and Prosecution?
A valid declaration under FAST-DS, accompanied by the prescribed payment and completion of the statutory process, can provide protection under the scheme in respect of the assets or income validly declared.
However, the protection is subject to the statutory conditions and exclusions.
Taxpayers should not assume that:
- Merely filing Form 1 automatically guarantees immunity.
- Every foreign asset is eligible.
- Pending proceedings always prevent participation.
- FAST-DS automatically cures FEMA violations.
- A declaration protects unrelated foreign income or assets.
In particular, section 140 contains specified exclusions, including certain matters connected with proceedings under the Prevention of Money-laundering Act, 2002 and completed assessments under the Black Money Act.
Section 141 also addresses the treatment of declarations where specified assessment proceedings are pending.
Accordingly, the appropriate position should be determined before filing a declaration or responding to any income-tax notice.
Foreign Property Ownership May Also Raise FEMA Questions
Ownership of overseas immovable property must be examined from both income-tax and foreign exchange perspectives.
The acquisition and transfer of foreign immovable property by residents are governed by the Foreign Exchange Management Act, 1999, the Foreign Exchange Management (Overseas Investment) Rules, 2022 and applicable RBI directions.
Relevant issues can include:
- Whether the property was acquired when the individual was resident or non-resident.
- Whether the acquisition was permitted under the applicable FEMA provisions.
- Whether remittances were made through authorised banking channels.
- Whether foreign borrowings or liabilities were created.
- Whether the property was acquired through inheritance, gift or another permitted route.
- Whether the source of funding and relevant banking records are available.
A foreign property may be properly disclosed for income-tax purposes but still require a separate FEMA compliance review.
Similarly, a permissible FEMA acquisition does not automatically satisfy Indian income-tax disclosure obligations.
Taxpayers should therefore examine both frameworks independently.
Practical Examples: How Different Foreign Property Cases May Be Treated
Example 1: Dubai Apartment Purchased Through LRS
An ordinarily resident Indian individual purchased an apartment in Dubai from tax-paid Indian income remitted through an authorised bank.
The property was not reported in Schedule FA.
The source of acquisition is explained, but the reporting failure needs to be examined under the Black Money Act.
Subject to eligibility, the ₹5 crore category under FAST-DS may be relevant.
Example 2: Property Acquired While Working Abroad
An individual acquired a residential property in the United States while qualifying as a non-resident under Indian income-tax law.
Several years later, the individual returned to India and became ordinarily resident but failed to disclose the overseas property.
The acquisition may have been legitimate and funded from foreign earnings.
Nevertheless, the subsequent Schedule FA omission requires review. The explained-asset category of FAST-DS may provide a remedy if its conditions are satisfied.
Example 3: Foreign Property Purchased From Unexplained Funds
A taxpayer owns an overseas property but cannot satisfactorily establish the source of investment.
This case presents a materially different risk.
Depending upon the evidence and applicable law, the property may be examined under the substantive provisions governing undisclosed foreign assets.
If the statutory conditions are satisfied, the first category of FAST-DS may require consideration.
Example 4: Overseas Property Held by an NRI
An individual has remained non-resident under Indian income-tax law during the relevant years and owns a property overseas.
The mere existence of that property does not ordinarily create Schedule FA reporting obligations for those non-resident years.
However, any subsequent change in residential status, Indian-source income and relevant historical reporting requirements must be considered separately.
What Should Foreign Property Owners Do Before 31 December 2026?
Individuals owning immovable property outside India should undertake a structured compliance review rather than assume that the property is either automatically taxable or exempt from disclosure.
The review should cover:
- Residential status: Determine NR, RNOR or ROR status for the relevant years.
- Property ownership: Identify the legal owner, beneficial owner, ownership percentage and date of acquisition.
- Source of funds: Reconcile purchase consideration with bank remittances, foreign earnings, inheritance, gifts or other documented sources.
- Past ITR filings: Examine Schedule FA, foreign-source income and other applicable disclosures.
- Income from property: Review rental income, property sales and any related foreign tax obligations.
- FEMA compliance: Verify acquisition and funding under applicable RBI rules.
- FAST-DS eligibility: Determine whether the case qualifies under either category before the statutory deadline.
The decision between a revised return, updated return, FAST-DS declaration or another statutory remedy depends on the relevant year and precise nature of the default. These options should not be treated as interchangeable.
Frequently Asked Questions
1. Is the Income Tax Department issuing notices for foreign property in 2026?
The Economic Times reported on 23 October 2026 that the Department is likely to issue notices concerning undisclosed overseas properties in the coming weeks. However, the specific exercise has not been independently verified through a formal CBDT announcement.
2. Is owning property in Dubai or another foreign country illegal for an Indian resident?
No. Foreign property ownership is not inherently illegal. It must comply with the applicable FEMA provisions and Indian tax reporting requirements.
3. Is foreign property purchased from tax-paid income required to be disclosed?
Generally, yes, where Schedule FA applies to the taxpayer. Legitimate or tax-paid acquisition does not automatically remove the annual disclosure requirement.
4. Can a foreign property worth less than ₹20 lakh escape Black Money Act reporting penalties?
The ₹20 lakh exclusion under the relevant provisions specifically excludes foreign immovable property. Therefore, the monetary relaxation should not be relied upon for an overseas apartment, building or land.
5. Can an NRI be penalised for not disclosing overseas property in Schedule FA?
Schedule FA is generally not applicable to a non-resident for the relevant year. However, earlier or subsequent resident years, actual residential status and other circumstances must be examined.
6. Can foreign property be declared under FAST-DS 2026?
Yes, qualifying foreign immovable property may be covered under the scheme, subject to its conditions and prescribed monetary thresholds.
7. What is the last date for FAST-DS 2026?
The last date to file the prescribed declaration in Form 1 is 31 December 2026.
Conclusion: Overseas Property Compliance Requires Immediate Review
The latest reports of potential Income Tax Department notices highlight the increasing importance of accurate foreign-asset disclosure by Indian residents.
However, the existence of a foreign property should not be equated with tax evasion.
The correct legal treatment depends upon the taxpayer’s residential status, the timing and source of acquisition, compliance with Schedule FA, and any foreign income generated from the property.
With FAST-DS 2026 available only until 31 December 2026, eligible taxpayers with historical foreign-property disclosure defaults should review their position before the deadline.
Timely verification of ownership, source of investment, income-tax disclosures and FEMA compliance may help taxpayers identify the appropriate statutory remedy and respond accurately to any subsequent enquiry.
For related guidance, visit CA Alok Kumar – Taxation, Foreign Assets and Legal Insights or read our complete FAST-DS 2026 disclosure guide.
Official References and Source
- The Economic Times, 23 October 2026: I-T likely to send notices over undisclosed foreign property.
- Finance Act, 2026: Chapter IV, sections 130–144 — Foreign Assets of Small Taxpayers Disclosure Scheme.
- CBDT Notification No. 114/2026, dated 14 August 2026: Foreign Assets of Small Taxpayers–Disclosure Scheme Rules, 2026.
- Income Tax Department: Official FAST-DS Form 1 FAQs.
- Income Tax Department: Schedule FA reporting guidance.
- Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015: Sections 3, 4, 41–43 and 49–50.
- Government of India: Budget 2026 FAQs concerning amendments to Black Money Act prosecution provisions.
- FEMA, 1999: Section 6, read with Rule 21 of the Foreign Exchange Management (Overseas Investment) Rules, 2022, and relevant RBI directions.
Disclaimer: This article is intended for professional and general information. Applicable tax, disclosure and foreign-exchange obligations depend upon individual facts and prevailing statutory provisions.
Leave a Reply