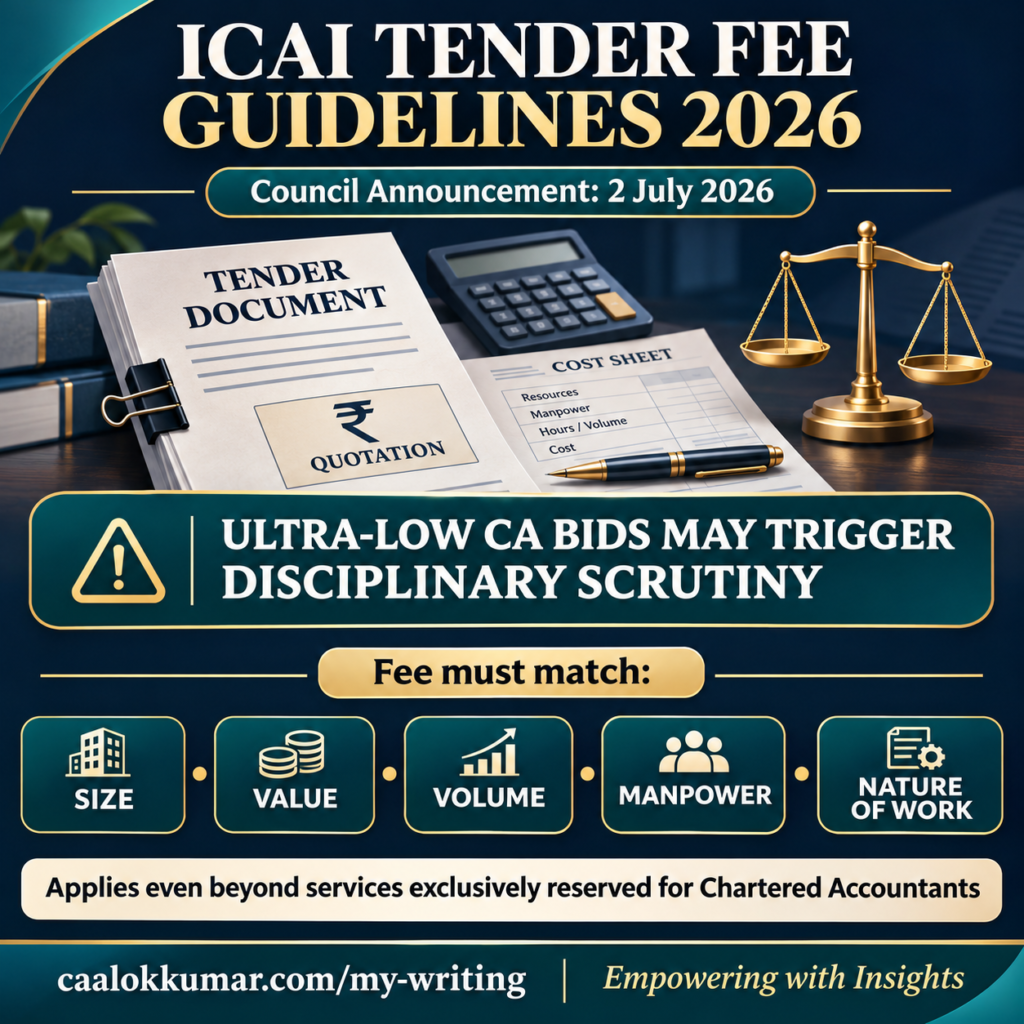
The Institute of Chartered Accountants of India has strengthened its regulatory approach towards professional fees quoted by Chartered Accountants and CA firms in tenders.
Under the latest ICAI tender fee guidelines, a tender quotation may be referred to the Director (Discipline) where the fee is extremely low and is not commensurate with the size, value, volume, manpower requirement and nature of the assignment.
The decision is significant because it applies whether or not the tender relates to a service exclusively reserved for Chartered Accountants.
For practising Chartered Accountants, the message is clear: a financial bid should reflect the actual professional effort, staffing requirement, responsibility, risk and scope of the assignment. Winning professional work through an economically unviable quotation may now create an ethical and disciplinary risk.
Important Correction Regarding the Effective Date
Certain online messages claim that the new guidelines became effective on 12 October 2026. This is not supported by the official ICAI announcement.
The official ICAI announcement is dated 2 July 2026 and is titled “Decision taken by the Council regarding tenders.” The announcement does not mention 12 October 2026 as its effective date.
Accordingly, the professional update should be described as the ICAI Council decision announced on 2 July 2026, rather than as a guideline effective from 12 October 2026.
Read the official ICAI announcement
What Has ICAI Decided?
The ICAI Council has decided that a matter may be referred to the Director (Discipline) where:
- the professional fee quoted by a member or CA firm is extremely low; and
- the quoted fee is not commensurate with the assignment’s size, value, volume, manpower requirement or nature of work.
The decision applies regardless of whether the tender concerns:
- audit or attestation work exclusively reserved for Chartered Accountants;
- advisory, accounting or consultancy services open to other professionals; or
- another professional assignment for which a CA or CA firm is eligible to bid.
The announcement does not state that every low bid will automatically amount to professional misconduct. It creates a mechanism under which an apparently unreasonable quotation can be referred for examination and appropriate action.
Why Has ICAI Introduced This Measure?
Extremely low quotations can affect more than the commercial interests of competing firms. They can create genuine concerns regarding:
- whether adequate qualified manpower will be deployed;
- whether the assignment can be completed within the required time;
- whether proper supervision and partner involvement will be available;
- whether sufficient audit evidence and documentation will be maintained;
- whether quality-control requirements can be complied with;
- whether the fee covers the responsibility and professional risk involved; and
- whether the bid compromises the dignity and quality of the profession.
A professional engagement cannot be evaluated merely by comparing the lowest financial quotation. Assignments such as statutory audit, tax audit, internal audit, certification, forensic review and compliance examination require trained staff, professional judgement, documentation, supervision and accountability.
Clients seeking reliable audit and assurance services should therefore evaluate professional competence, experience, independence, staffing and execution methodology alongside the financial bid.
Factors Relevant for Determining Whether a Fee Is Extremely Low
The July 2026 ICAI announcement identifies five important parameters.
1. Size of the assignment
The professional fee should reflect the size of the entity, number of locations, branches, transactions, accounts and reporting units involved.
2. Value involved
The financial magnitude and potential exposure associated with the engagement are relevant. An assignment involving high-value transactions or substantial public funds ordinarily carries greater responsibility and risk.
3. Volume of work
The number of vouchers, contracts, bank accounts, GST registrations, employees, assets, confirmations or samples to be examined may significantly affect the time required.
4. Manpower requirement
The quotation should consider the number and level of professionals required, including:
- engagement partner;
- qualified Chartered Accountants;
- semi-qualified assistants;
- article assistants;
- audit executives;
- subject-matter specialists; and
- information-technology or forensic-audit personnel.
5. Nature of work
A routine certification assignment cannot necessarily be compared with a statutory audit, forensic investigation, concurrent audit or complex regulatory review.
For example, professional effort in a tax audit under Section 44AB depends upon turnover, accounting systems, volume of transactions, tax positions, GST and TDS reconciliations, reporting requirements and the quality of books maintained by the assessee.
Does ICAI Now Prescribe a Compulsory Minimum Fee?
No fixed compulsory fee has been prescribed by the July 2026 announcement.
ICAI publishes a Minimum Recommended Scale of Fees for different professional assignments. However, the published scale is recommendatory. The accompanying notes recognise that the actual fee may vary depending upon:
- nature and complexity of the engagement;
- time required to complete the work;
- location of the professional;
- travelling and out-of-pocket expenditure; and
- the agreement between the member and the client.
The new decision should therefore not be interpreted as statutory price fixing or as a uniform fee applicable to every assignment.
The real requirement is that the quotation should be rational, professionally defensible and reasonably connected with the resources necessary to execute the engagement properly.
Visit ICAI’s Minimum Recommended Fee resources
How the 2026 Decision Differs from the 2016 Tender Guidelines
| Particular | ICAI guidelines dated 7 April 2016 | ICAI Council decision dated 2 July 2026 |
| Primary concern | Whether a member may respond to a tender | Whether the fee quoted is extremely low |
| Reserved services | Restricts tenders exclusively reserved for CAs unless an exception applies | Applies even if the service is not exclusively reserved for CAs |
| Minimum fee in tender | Participation permitted where the tender itself prescribes a minimum fee | A quoted fee may still be examined for commercial reasonableness |
| Other professionals | Participation permitted where the service is also open to other professionals | Extremely low fees may nevertheless invite scrutiny |
| Regulatory consequence | Contravention may constitute professional misconduct | Matter may be referred to the Director (Discipline) |
The two requirements must be read together.
First, a CA firm should determine whether it is ethically permitted to participate in the tender under the 2016 guidelines. Second, even where participation is permitted, the financial quotation should not be so low that it is inconsistent with the assignment’s scope and resource requirements.
Existing Rule for Tenders Covering Reserved CA Services
Guideline No. 1-CA(7)/03/2016 was issued under Item (1) of Part II of the Second Schedule to the Chartered Accountants Act, 1949.
It provides that a member in practice should not respond to a tender for services exclusively reserved for Chartered Accountants, such as audit and attestation services, unless:
- the tender document itself prescribes a minimum fee; or
- the assignment is also open to other professionals along with Chartered Accountants.
The 2016 announcement further clarified that a member contravening the guidelines may face disciplinary action under Section 21 of the Chartered Accountants Act, 1949.
Read ICAI Guideline No. 1-CA(7)/03/2016
GeM Tenders Are Also Covered
ICAI has separately clarified that practising Chartered Accountants and CA firms may register on the Government e-Marketplace portal for rendering professional services.
However, the tender guidelines dated 7 April 2016 continue to apply to professional tenders floated through the GeM portal.
Therefore, registration on GeM does not remove a member’s responsibility to examine:
- whether the tender relates to an exclusively reserved service;
- whether the tender prescribes a minimum fee;
- whether other professionals are eligible;
- whether the quotation is commercially reasonable; and
- whether all information published by the firm complies with the ICAI Code of Ethics.
Read ICAI’s clarification regarding registration on GeM
Practical Tender Compliance Checklist for CA Firms
Before submitting a tender, the member or firm should document the following:
Eligibility review
- Determine whether the assignment is exclusively reserved for Chartered Accountants.
- Check whether the tender prescribes a minimum fee.
- Verify whether other professionals are permitted to participate.
- Examine independence, conflict-of-interest and rotation requirements.
Scope assessment
- Read the complete tender, corrigenda and pre-bid clarifications.
- Identify locations, branches, transaction volume and reporting deadlines.
- Record deliverables, certificates, presentations and management meetings required.
- Note whether specialised tax, information-technology or forensic skills are needed.
Manpower planning
- Estimate partner and manager hours.
- Determine the number of qualified and semi-qualified personnel required.
- Consider travel, accommodation and out-of-pocket expenses.
- Provide time for documentation, supervision and quality review.
Fee computation
- Prepare an engagement-wise cost sheet.
- Record the assumptions used for estimating hours and costs.
- Compare the proposed quotation with ICAI’s recommended scale of fees.
- Document commercial reasons for any significant variation.
- Add GST and reimbursable expenditure appropriately.
Bid approval and record retention
- Obtain approval from the partner or authorised tender committee.
- Retain the tender document, technical bid, financial bid and workings.
- Preserve correspondence and pre-bid clarifications.
- Maintain evidence demonstrating that the quotation was professionally and commercially justified.
A documented fee calculation will be important if the quotation is subsequently questioned.
CA firms may integrate this review with their broader accounting and Virtual CFO systems, particularly where tender costing, manpower allocation and engagement profitability are centrally monitored.
Implications for Organisations Inviting CA Tenders
The ICAI decision is also relevant for companies, banks, government bodies, PSUs, societies and other organisations inviting professional bids.
Tendering authorities should avoid designing a process that treats the lowest price as the only meaningful criterion. An appropriate evaluation may consider:
- experience in similar assignments;
- technical competence;
- proposed audit methodology;
- partner and team involvement;
- geographical capability;
- independence and conflict checks;
- peer-review status, wherever relevant;
- information-security arrangements;
- quality-control systems; and
- reasonableness of the professional fee.
Organisations planning a tender may obtain business consulting and strategic advisory support for defining the scope, deliverables, eligibility conditions and evaluation methodology.
Businesses at the incorporation or expansion stage may also use company formation and compliance support to establish appropriate accounting, governance and audit frameworks.
Can a Lower Fee Still Be Justified?
Yes. A lower fee does not automatically mean that the bid is unethical.
A CA firm may legitimately quote a competitive fee because of:
- technology-enabled audit procedures;
- an established team already present at the location;
- reduced travel requirements;
- standardised working-paper systems;
- efficiencies gained from similar assignments;
- a narrower or clearly defined scope; or
- lower operational costs.
However, those efficiencies should be documented. The quotation should still provide for appropriate professional time, supervision, review, documentation and quality control.
The distinction is between a commercially competitive bid and an unrealistically low bid that cannot reasonably support proper execution of the assignment.
Frequently Asked Questions
1. What are the latest ICAI tender fee guidelines?
ICAI announced on 2 July 2026 that where a member or CA firm quotes an extremely low fee that is not commensurate with the size, value, volume, manpower requirement and nature of the assignment, the matter may be referred to the Director (Discipline).
2. Are the new guidelines effective from 12 October 2026?
The official ICAI announcement does not prescribe 12 October 2026 as the effective date. The verified Council announcement is dated 2 July 2026.
3. Does every low tender quotation amount to professional misconduct?
No. The announcement provides for referral and examination. Whether disciplinary action is warranted would depend upon the facts, applicable guidelines, explanation of the member and the disciplinary process under the Chartered Accountants Act.
4. Are ICAI’s recommended fees compulsory?
The published scale is recommendatory. Actual professional fees may vary according to the complexity, time, scope, location and commercial agreement. However, an extremely low and unjustifiable fee may now invite scrutiny.
5. Can a CA respond to an audit tender without a prescribed minimum fee?
Where the service is exclusively reserved for Chartered Accountants, the 2016 guidelines generally restrict participation unless the tender prescribes a minimum fee or the assignment is also open to other professionals.
6. Do ICAI tender guidelines apply to GeM tenders?
Yes. ICAI has clarified that its tender guidelines apply to tenders floated through the Government e-Marketplace portal.
7. What records should a CA firm maintain before submitting a bid?
The firm should maintain the tender document, scope analysis, manpower plan, estimated professional hours, cost sheet, fee calculations, approvals, technical proposal and financial bid.
Conclusion
The updated ICAI tender fee approach represents an important shift from examining only whether a Chartered Accountant may participate in a tender to also examining whether the professional fee quoted is reasonable in relation to the work.
The decision does not create a compulsory uniform fee. It does, however, require members and CA firms to ensure that their bids are commercially rational, adequately documented and capable of supporting a professionally compliant engagement.
For every tender, the firm should evaluate eligibility, scope, manpower, responsibility, professional risk, quality-control requirements and realistic execution costs before submitting its financial bid.
The lowest bid may win the assignment—but an indefensibly low bid may now invite questions from the regulator.
Disclaimer
This article is intended for general professional information and education. It does not constitute legal, disciplinary or professional advice. Members should examine the applicable ICAI Code of Ethics, Council guidelines, official announcements, tender conditions and the specific facts before participating in any tender.
#ICAI #CharteredAccountants #CATenderGuidelines #ProfessionalFees #AuditTender #CodeOfEthics #CAFirm #ProfessionalMisconduct #AuditQuality #ICAIUpdates
Leave a Reply