Breaking News | 24 October 2026 | MCA & ROC Compliance Update
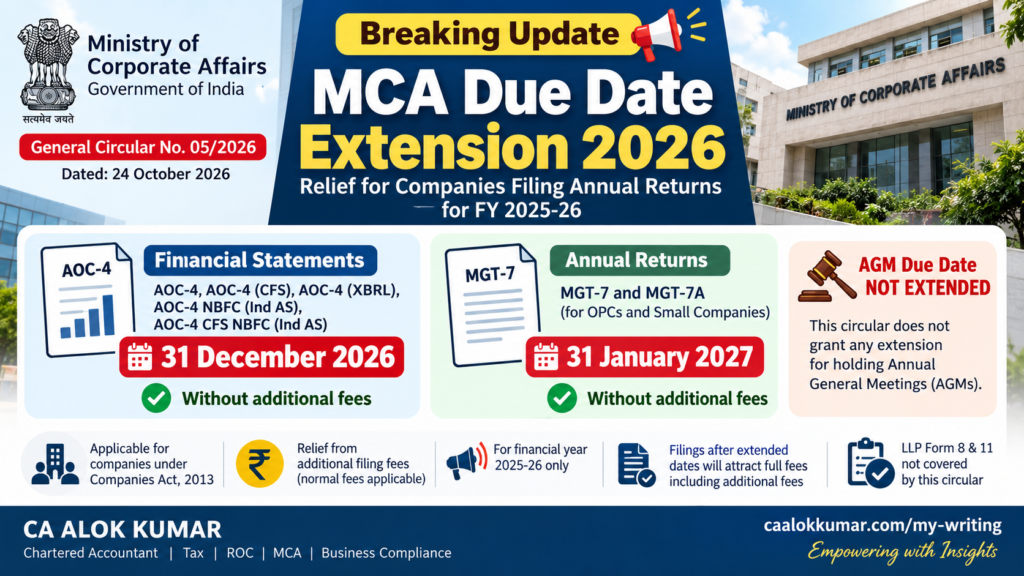
MCA Due Date Extension 2026: The Ministry of Corporate Affairs (MCA), through General Circular No. 05/2026 dated 24 October 2026, has announced a major relaxation for companies filing annual financial statements and annual returns for the financial year 2025-26.
Under the circular, companies can file AOC-4 and related financial statement forms up to 31 December 2026, while MGT-7 and MGT-7A annual returns can be filed up to 31 January 2027, without payment of additional filing fees.
This is significant relief for private limited companies, public companies, small companies, One Person Companies (OPCs), startups and other companies covered by the prescribed annual filing forms.
However, MCA has expressly clarified that the relaxation does not extend the statutory deadline for holding Annual General Meetings (AGMs).
Breaking MCA Update: New AOC-4 and MGT-7 Filing Dates
According to paragraph 2 of MCA General Circular No. 05/2026, the relaxation has been granted following representations received from stakeholders seeking additional time to complete annual statutory filings under the Companies Act, 2013.
The Ministry has provided separate deadlines for financial statements and annual returns.
Revised MCA Filing Deadlines for FY 2025-26
| ROC Form | Filing purpose | New last date |
|---|---|---|
| AOC-4 | Filing of financial statements | 31 December 2026 |
| AOC-4 (CFS) | Consolidated financial statements | 31 December 2026 |
| AOC-4 (XBRL) | Financial statements in XBRL format | 31 December 2026 |
| AOC-4 NBFC (Ind AS) | Financial statements of applicable NBFCs | 31 December 2026 |
| AOC-4 CFS NBFC (Ind AS) | Consolidated financial statements of applicable NBFCs | 31 December 2026 |
| MGT-7 | Annual return of applicable companies | 31 January 2027 |
| MGT-7A | Annual return of OPCs and small companies | 31 January 2027 |
All the above forms may be filed within the respective extended periods without additional fees, subject to the circular. Normal statutory filing fees remain payable.
The relaxation is specifically applicable to the financial year 2025-26, ending 31 March 2026.
For detailed assistance regarding ROC annual filing, AOC-4 and MGT-7 compliance, companies may review their pending filings and prepare the required documents.
What Has Changed Under MCA General Circular 05/2026?
Under the ordinary provisions of the Companies Act, 2013:
- Section 137: Financial statements are generally required to be filed within 30 days of the AGM.
- Section 92(4): Annual returns are generally required to be filed within 60 days of the AGM.
For a company whose financial year ended on 31 March 2026 and which held its AGM on 30 September 2026, the ordinary filing dates would generally have been:
| Compliance | Ordinary deadline | Relaxed filing date |
|---|---|---|
| AOC-4 | 30 October 2026 | 31 December 2026 |
| MGT-7 / MGT-7A | 29 November 2026 | 31 January 2027 |
The ordinary dates can vary where the AGM was held earlier, was not held, or a different statutory filing framework applies.
The significant point is that the circular provides additional time for filing the specified forms without additional fees. It does not rewrite the underlying statutory provisions governing annual filings.
Readers may also refer to our complete annual ROC filing checklist for companies.
Important Clarification: AGM Due Date Has Not Been Extended
One of the most important conditions appears in paragraph 3 of the MCA circular.
The Ministry expressly states that the circular shall not be construed as granting an extension of statutory time for holding AGMs.
Under Section 96 of the Companies Act, 2013, companies are generally required to hold their AGMs within the applicable statutory time limits.
For companies following a financial year ending 31 March 2026, the ordinary AGM deadline was generally 30 September 2026, subject to applicable exceptions and valid extensions.
Therefore, companies that failed to hold their AGM within the legally permitted time cannot rely upon General Circular No. 05/2026 as an extension of that deadline.
A default in holding an AGM may attract consequences under Section 99 of the Companies Act, 2013.
In simple terms: MCA has relaxed additional filing fees for specified annual forms, but it has not regularised delayed or unheld AGMs.
Does the MCA Extension Provide Complete Waiver of ROC Penalties?
No. The circular must be interpreted carefully.
It provides relief from additional filing fees for the specified forms during the permitted period.
It does not expressly waive every statutory penalty or liability arising under the Companies Act, 2013.
A distinction must be maintained between:
- Normal filing fees: The prescribed filing fees remain applicable.
- Additional filing fees: These are relaxed for the specified forms filed within the extended period.
- Statutory penalties: Any separate liability arising from non-compliance with provisions of the Act is not expressly waived by this circular.
For example, a company that failed to hold its AGM within the legally permitted period may still face consequences despite filing AOC-4 and MGT-7 within the relaxed filing windows.
What Happens After the Extended Deadlines?
Paragraph 4 of the circular clarifies that filings made after the relaxation period will attract fees, including additional fees, as provided under the Companies (Registration Offices and Fees) Rules, 2014, calculated with reference to the dates on which the filings were originally due under the Act.
Therefore, companies should not assume that additional fees will begin accumulating only from 1 January 2027 or 1 February 2027.
Missing the extended filing window could result in substantial additional fees calculated with reference to the original statutory due date.
Which Companies Can Benefit From the MCA Annual Filing Extension?
The relaxation is relevant to companies required to file the specified forms, including:
- Private limited companies.
- Public limited companies.
- Small companies.
- One Person Companies.
- Section 8 companies, where the specified forms apply.
- Companies required to file XBRL financial statements.
- Applicable NBFCs following Indian Accounting Standards.
The precise form depends on the company’s classification and applicable reporting requirements.
The circular does not provide a general extension for every MCA filing.
For example, it does not expressly extend ADT-1, DIR-12, DPT-3, MSME-1, LLP Form 8 or LLP Form 11.
Accordingly, companies and LLPs should continue to comply with the statutory deadlines applicable to forms not covered by the circular.
What About LLP Annual Filing Due Dates?
An important clarification for business owners is that the present relaxation concerns specified filings under the Companies Act, 2013.
It does not expressly extend the deadlines for annual filings under the Limited Liability Partnership Act, 2008.
Therefore, LLP Form 8 and Form 11 should not be treated as covered by this circular.
For business owners requiring assistance with company and LLP compliance, our ROC filing and corporate compliance services cover statutory filings, documentation and related MCA requirements.
Practical Impact of the Extension for Companies and Professionals
The extension is particularly useful for companies facing difficulties in completing annual filing formalities on the MCA V3 portal.
The annual filing process may involve:
- Finalisation and audit of financial statements.
- Preparation and approval of the Board’s Report.
- Preparation of consolidated financial statements, where applicable.
- Compilation of shareholder and shareholding information.
- Validation of company master data.
- Preparation of annual return details.
- Digital Signature Certificate verification.
- Uploading attachments and resolving MCA portal validation errors.
The additional filing window can help reduce last-minute filing pressure and facilitate better compliance.
Companies using the new filing utilities may also refer to our article on MCA V3 offline annual filing for AOC-4 and MGT-7.
Nevertheless, the extension should not be treated as a reason to postpone finalisation of statutory records.
MCA Filing Extension 2026 vs CCFS 2026: Important Difference
There may be confusion between the latest annual filing relaxation and the earlier Companies Compliance Facilitation Scheme, 2026 (CCFS-2026).
These are separate measures.
The earlier CCFS-2026 provided a compliance facilitation mechanism for eligible pending filings, subject to its own conditions.
The latest General Circular No. 05/2026 specifically grants additional-fee relief for the listed annual filing forms relating to FY 2025-26.
Companies should not assume that the latest circular reopens CCFS-2026 or extends its benefits to earlier years.
For background, read our earlier coverage of the CCFS 2026 extension and pending ROC filings.
What Should Companies Do Now?
Companies, directors, CFOs, accounts teams and compliance professionals should use the available time to complete all pending statutory work.
The following steps are advisable:
- Finalise the audited financial statements and ensure that the necessary approvals and signatures are complete.
- Verify AGM compliance, including the date of holding the AGM and the required statutory documentation.
- Prepare AOC-4 or the applicable variant and complete filing by 31 December 2026.
- Prepare MGT-7 or MGT-7A and complete filing by 31 January 2027.
- Review MCA V3 master data, DSC association, shareholding details and previous filing records.
- Check other statutory forms separately, because the latest relaxation is restricted to the forms expressly identified in the circular.
Professional review is particularly important where companies have pending filings for earlier financial years, unfiled financial statements, AGM defaults, incorrect master data or unresolved MCA portal issues.
Frequently Asked Questions on MCA Due Date Extension 2026
1. Has MCA extended the AOC-4 filing due date for FY 2025-26?
Yes. As stated in General Circular No. 05/2026 dated 24 October 2026, filing of AOC-4 and the specified related forms is permitted up to 31 December 2026 without additional fees.
2. What is the new MGT-7 filing deadline?
The circular permits filing of MGT-7 and MGT-7A up to 31 January 2027 without additional fees for FY 2025-26.
3. Is the AGM deadline also extended?
No. MCA has expressly clarified that the circular does not extend the statutory time for holding AGMs.
4. Are late filing fees completely waived?
Additional filing fees are relaxed for the specified forms filed within the permitted period. Normal filing fees continue to apply. Other statutory liabilities are not automatically waived.
5. Is the extension applicable to LLP Form 8 and Form 11?
No. The circular does not include LLP Form 8 or Form 11.
6. Does the extension cover annual filing forms for FY 2024-25?
No. General Circular No. 05/2026 specifically refers to filings for FY 2025-26.
7. What happens if AOC-4 or MGT-7 is filed after the extended deadline?
The circular provides that applicable fees, including additional fees, will be payable with reference to the original statutory due date under the Act.
Conclusion: Significant Relief for ROC Annual Filing in 2026
MCA General Circular No. 05/2026 dated 24 October 2026 provides significant relief to companies completing annual statutory filings for FY 2025-26.
The two important dates are:
31 December 2026 — AOC-4 and specified financial statement forms.
31 January 2027 — MGT-7 and MGT-7A annual returns.
The relief applies to additional filing fees for the specified forms and does not extend the statutory time for holding AGMs.
Companies should use this opportunity to complete their pending annual filings accurately and avoid potential additional fees after the relaxed filing period.
For professional guidance on ROC filing services, company annual returns, AOC-4, MGT-7 and MCA compliance, visit CA Alok Kumar.
Legal References and Sources
Primary notification: Ministry of Corporate Affairs, General Circular No. 05/2026, dated 24 October 2026, File No. Policy-17/111/2022-CL-V-MCA, titled Relaxation of additional fees and extension of time for filing of Financial Statements and Annual Returns under the Companies Act, 2013.
Relevant statutory provisions:
- Companies Act, 2013 — Section 92(4), filing of annual returns.
- Companies Act, 2013 — Section 96, Annual General Meetings.
- Companies Act, 2013 — Section 99, consequences of default in holding AGMs.
- Companies Act, 2013 — Section 137, filing of financial statements.
- Companies (Registration Offices and Fees) Rules, 2014 — applicable filing and additional fees.
Official verification portal: Ministry of Corporate Affairs.
Disclaimer: This article is based on the text of General Circular No. 05/2026 dated 24 October 2026 supplied for review. The circular’s availability on the official MCA portal should be checked. Application of the relaxation and any separate statutory consequences depend upon the relevant facts and applicable law.
Leave a Reply