FAST-DS 2026 Advisory Email: What Taxpayers Should Check Before Filing Form 1
Updated: 6 October 2026
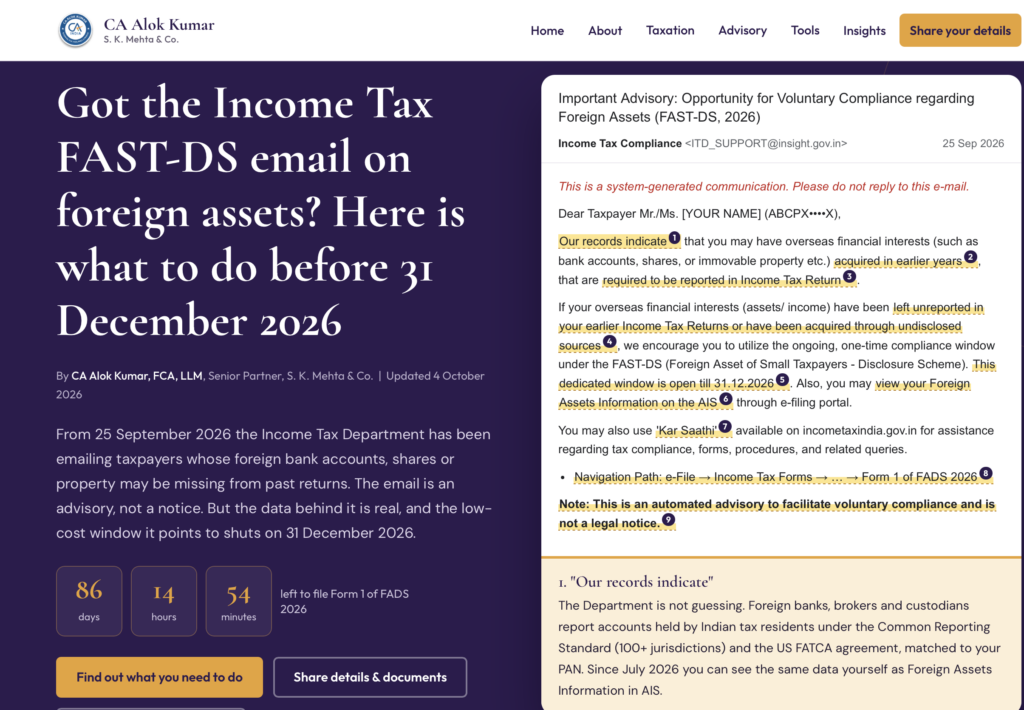
The Income Tax Department has recently started sending taxpayers a system-generated communication titled:
“Important Advisory: Opportunity for Voluntary Compliance regarding Foreign Assets (FAST-DS 2026)”
The advisory states that departmental records indicate that a taxpayer may have overseas financial interests, such as foreign bank accounts, shares, securities, immovable property or other foreign assets acquired in earlier years, which may have been required to be reported in the Income Tax Return.
It also asks taxpayers to review their Foreign Assets Information in AIS and, where applicable, consider the one-time voluntary compliance window under the Foreign Assets of Small Taxpayers – Disclosure Scheme, 2026, popularly known as FAST-DS 2026.
The Department’s email contains an important clarification:
“This is an automated advisory to facilitate voluntary compliance and is not a legal notice.”
That distinction matters.
Receiving a FAST-DS advisory email does not by itself mean that the taxpayer has concealed foreign income, owns an undisclosed foreign asset or has become liable to pay either ₹1 lakh or 60% under FAST-DS.
But the email should not be ignored either.
The appropriate response is to identify the overseas asset or income appearing in departmental information, examine the taxpayer’s residential status and source of acquisition, compare the information with earlier ITRs and Schedule FA disclosures, and only then determine whether FAST-DS filing is required.
For detailed eligibility analysis, valuation guidance and professional assistance, taxpayers may refer to our FAST-DS 2026 – Foreign Assets Disclosure Scheme filing and compliance page.
Why Is the Income Tax Department Sending FAST-DS Advisory Emails?
The advisory needs to be understood in the context of India’s increasing access to overseas financial information.
CBDT announced in July 2026 that taxpayers can view Foreign Assets Information received through CRS/FATCA arrangements in the Annual Information Statement (AIS). The Income Tax Department specifically lists the availability of Foreign Asset Information in AIS as part of its taxpayer-service initiative. Income Tax Department
The Government’s own FAST-DS material explains that non-disclosure has particularly arisen in cases involving foreign ESOPs or RSUs, dormant or low-value overseas bank accounts, savings or insurance policies of returning non-residents and assets of persons who had worked or been deputed overseas. It also refers to information received through the Automatic Exchange of Information framework. Etds
The present advisory campaign is therefore significant.
It effectively gives taxpayers an opportunity to review historical foreign-asset reporting before deciding whether there is anything that requires regularisation under FAST-DS.
Recent reporting also confirms that the Department has been sending emails/messages sharing information relating to overseas accounts, stocks and other foreign assets with taxpayers. The Indian Express
What Does the FAST-DS Advisory Email Mean?
The email is a voluntary-compliance advisory, not a statutory assessment, reassessment, penalty or prosecution notice.
It should nevertheless trigger a proper review because the communication indicates that information relating to overseas financial interests may be available against the taxpayer’s PAN.
There can be several explanations.
A foreign bank account may have been opened while the taxpayer was a non-resident. Overseas shares may have arisen from foreign employment. RSUs may already have been taxed as salary. A foreign investment may have been acquired from fully disclosed income. The asset may even have been correctly reported in Schedule FA.
Therefore:
A foreign asset is not automatically an undisclosed foreign asset.
Likewise:
An omission from Schedule FA is not automatically undisclosed income.
Those distinctions are central to FAST-DS compliance.
Taxpayers who want to understand ordinary foreign-asset reporting requirements should also read our Foreign Assets in ITR – Schedule FA and Foreign Income guide. The page deals separately with Schedule FA, foreign income, overseas shares, foreign accounts and Foreign Tax Credit. CA Alok Kumar
What Is FAST-DS 2026?
The Foreign Assets of Small Taxpayers – Disclosure Scheme, 2026 is a one-time statutory disclosure scheme contained in Chapter IV, sections 130 to 144 of the Finance Act, 2026.
It enables eligible taxpayers to disclose specified:
undisclosed foreign assets, undisclosed foreign income and certain foreign assets whose source was legitimate or already taxed but which were not reported in the relevant return schedule.
The Scheme came into force on 16 August 2026.
Its prescribed valuation date is 31 March 2026.
The last date for filing a declaration is:
31 December 2026
The official FAQs state that no declaration can be filed after that date. FAST-DS-FAQs it
The Income Tax Department has also activated Form 1 of FADS 2026 for electronic filing. Income Tax Department
For readers seeking the broader statutory background, our complete FAST-DS 2026 guide explains the Scheme separately. CA Alok Kumar
FAST-DS Has Two Very Different Compliance Routes
This is probably the most important issue in the entire Scheme.
FAST-DS does not impose the same financial consequence on every unreported foreign asset.
Section 133 broadly distinguishes between two categories. FAST-DS-FAQs it
Route 1: Undisclosed Foreign Asset or Undisclosed Foreign Income
This route broadly covers:
undisclosed foreign income which was chargeable to tax in India but was not offered to tax; or
an undisclosed asset located outside India, including a financial interest in a foreign entity, where the source of investment is unexplained or the explanation is considered unsatisfactory.
The aggregate value of qualifying undisclosed foreign assets and undisclosed foreign income must not exceed ₹1 crore. FAST-DS-FAQs it
Amount payable under Route 1
The Scheme prescribes:
30% tax + an additional amount equal to that tax.
Accordingly, the combined amount payable effectively works out to:
60% of the value/income covered
The Department’s own example illustrates:
| Particular | Amount |
| Undisclosed foreign bank account | ₹60 lakh |
| Undisclosed foreign income | ₹20 lakh |
| Aggregate | ₹80 lakh |
| Tax @ 30% | ₹24 lakh |
| Additional amount equal to tax | ₹24 lakh |
| Total payable | ₹48 lakh |
This is why it is more accurate to say “effective FAST-DS outgo of 60%” rather than describing 60% as the statutory tax rate. FAST-DS-FAQs it
Route 2: Source Is Explained, but Foreign Asset Reporting Was Missed
The second category is fundamentally different and may be particularly relevant to employees, returning NRIs and taxpayers with old overseas investments.
It covers specified assets situated outside India which were broadly:
acquired out of income already offered to tax in India; or
acquired out of foreign income while the taxpayer was a non-resident,
but were not disclosed in the relevant schedule of the Income Tax Return when disclosure became applicable.
The aggregate value of the qualifying assets must not exceed ₹5 crore. FAST-DS-FAQs it
Amount payable under Route 2
The prescribed amount is:
₹1,00,000 flat fee
subject to the statutory conditions and ₹5 crore ceiling. FAST-DS-FAQs it
This distinction is particularly important for Schedule FA non-disclosure cases.
An overseas asset acquired from already-taxed income should not automatically be classified as an asset acquired from undisclosed income merely because Schedule FA was omitted.
The source of investment, acquisition history and residential status must first be established.
Common Cases That Should Be Reviewed After Receiving the FAST-DS Email
The Government’s own FAST-DS guidance identifies several types of taxpayers for whom the Scheme may be particularly relevant. Etds
A common example is an employee of a multinational company who received foreign RSUs, ESOPs or ESPP shares. The employment benefit may already have been taxed as salary, while the overseas shareholding itself was inadvertently omitted from Schedule FA.
Another example is a taxpayer who opened a foreign salary account while non-resident, subsequently returned to India and continued to maintain that account after becoming resident.
Similar issues can arise with overseas brokerage accounts, foreign mutual funds, retirement accounts, insurance policies, foreign property, interest, dividends, rent or capital gains.
For returning NRIs, residential status and the year of acquisition are particularly important. Our NRI Taxation & FEMA Services page explains the wider residential-status, DTAA, taxation and FEMA framework. CA Alok Kumar
Received a FAST-DS Advisory Email? Follow This Review Before Filing Form 1
A taxpayer should not begin with the question:
“How do I file FAST-DS?”
The better first question is:
“Is there actually a foreign-asset or foreign-income default, and if so, what type of default is it?”
A sensible review should cover:
- Verify the communication independently. Log in directly to the Income Tax e-Filing portal rather than making any payment merely because an email has been received.
- Review Foreign Assets Information in AIS. Identify the overseas account, shares, custodian, investment or other financial interest appearing in departmental information.
- Determine the acquisition history. Establish when each foreign asset was acquired or each account was opened.
- Determine residential status year by year. FAST-DS expressly accommodates certain taxpayers who are presently non-resident or RNOR but were resident in India during the relevant earlier period. FAST-DS-FAQs it
- Trace the source of investment. Determine whether the asset came from foreign salary while non-resident, already-taxed Indian income, disclosed remittances, inheritance, gift, business income or income that was never offered to Indian tax.
- Compare earlier Income Tax Returns. Review Schedule FA, Schedule FSI, Schedule TR, foreign income, salary, capital gains, interest, dividends and Foreign Tax Credit.
- Determine the correct statutory category and Rule 3 valuation.
- File Form 1 only after the legal and factual position is reasonably clear.
Where foreign tax has already been paid, the availability and procedural requirements of Foreign Tax Credit and Form 67should also be examined independently. CA Alok Kumar
FAST-DS Foreign Bank Account Valuation: Closing Balance Is Not the Test
Foreign bank accounts require particular attention under FAST-DS filing.
A taxpayer should not assume that the value of a foreign account is simply its:
current balance, year-end balance or peak balance.
Under Rule 3, the relevant value is broadly determined by aggregating deposits made into the account from the date it was opened up to the valuation date, subject to the specific exclusions prescribed in the Rules.
Where a subsequent deposit represents money earlier withdrawn from the same account, the prescribed mechanism prevents the same funds from being counted again. FAST-DS-FAQs it
The Department’s official illustration shows an overseas account opened in 2010 where historical deposits and withdrawals are reconstructed to arrive at a value of US$4,900, which is thereafter converted into Indian Rupees as on 31 March 2026. FAST-DS-FAQs it
This means that an overseas account having only a small balance today may still require several years of historical bank statements for FAST-DS purposes.
FAST-DS Foreign Bank Account Valuation Tool
For a preliminary working, taxpayers may use the foreign bank-account valuation tool available on our FAST-DS 2026 filing and compliance page. The tool applies the Rule 3(1)(e) deposit-based approach and allows redeposits funded from earlier withdrawals from the same account to be identified separately. CA Alok Kumar
The calculator is an independent assistance tool and not an Income Tax Department utility. The final value should therefore be verified against the original bank statements, foreign-currency conversion requirements and the notified Rules before Form 1 is filed.
How Are Other Foreign Assets Valued Under FAST-DS?
FAST-DS does not prescribe one valuation rule for every asset.
Quoted shares and securities generally involve the prescribed market-price methodology.
Unquoted equity shares require a prescribed formula-based valuation.
Foreign immovable property, jewellery and certain other assets broadly require comparison of acquisition cost with prescribed open-market value.
Interests in foreign partnerships, associations or LLPs are valued using the prescribed net-asset allocation methodology. FAST-DS-FAQs it
All values ultimately have to be expressed in Indian Rupees, using the conversion mechanism prescribed by the Rules. FAST-DS-FAQs it
For assets other than bank accounts, Rule 5(2) also provides a limited safeguard where a subsequently determined FMV differs from the declared FMV by not more than 20%, subject to the conditions of the Rule. FAST-DS-FAQs it
That provision is a protection for genuine valuation differences—not permission to deliberately undervalue an asset.
FAST-DS Filing: How Form 1 Works
FAST-DS declarations are filed electronically in Form 1 of FADS 2026.
The Income Tax Department’s official Form 1 user manual provides the current navigation:
e-File → Income Tax Forms → File Income Tax Forms → Forms as per Other Acts → Foreign Assets of Small Taxpayers Disclosure Scheme, 2026 → Form 1. Income Tax Department
Form 1 contains separate annexures depending upon whether the declaration concerns:
undisclosed foreign assets, undisclosed foreign income, foreign assets acquired while non-resident, or foreign assets acquired from income already offered to Indian tax.
The Department’s user manual confirms that the form separately captures bank accounts, immovable property, jewellery, artistic works, shares/securities and other assets. Income Tax Department
Supporting documents evidencing acquisition of the asset or earning of foreign income are required, together with valuation reports where applicable. FAST-DS-FAQs it
Readers who encounter difficulty identifying forms on the post-April-2026 e-Filing portal may also use our independent Income Tax Form Finder – 1961 Act ⇄ 2025 Act. CA Alok Kumar
FAST-DS Form 1 to Form 4: Complete Compliance Process
FAST-DS compliance does not end when Form 1 is submitted.
| Form | Purpose | Broad statutory process |
| Form 1 | Taxpayer’s declaration | Filed electronically by 31 December 2026 |
| Form 2 | Determination of amount payable | Issued by prescribed authority |
| Form 3 | Intimation and proof of payment | Filed by taxpayer after payment |
| Form 4 | Certification of valid declaration/payment | Issued after verification |
The authority ordinarily communicates the amount payable through Form 2 within one month from the end of the month in which the declaration was made.
The amount is ordinarily payable within two months from the end of the month in which the order is received. A limited further period can be used with simple interest at 1% for every month or part thereof, subject to the Scheme’s outer limit. FAST-DS-FAQs it
FAST-DS payments are made through Challan ITNS 289 after the taxpayer has filed a valid declaration and received the Form 2 order determining the amount payable. Income Tax Department
After payment, Form 3 must still be furnished. Payment alone does not complete the compliance cycle. The prescribed authority thereafter issues Form 4. Income Tax Department
FAST-DS vs Revised Return or ITR-U: Which Remedy Actually Applies?
This section deserves particular care because FAST-DS, a revised return and an Updated Return are different statutory remedies.
A taxpayer who receives the FAST-DS advisory may naturally ask:
“Instead of FAST-DS, can I simply revise or update my earlier Income Tax Return?”
There is no universal yes-or-no answer.
The correct route depends upon the year involved, nature of the omission, taxability of the foreign income, source of the asset, information already communicated by the Department and the statutory conditions governing each remedy.
Revised Return under Section 139(5)
For assessment years governed by the Income-tax Act, 1961, a revised return under section 139(5) is a mechanism for correcting an omission or wrong statement in an earlier return, but only within the prescribed statutory period.
Accordingly, where that time limit has already expired—as will normally be the position for older assessment years—a revised return cannot simply be filed now to cure an historical foreign-asset omission.
Where the revised-return window is still legally open, however, the taxpayer should separately determine whether correction through the return is appropriate.
Updated Return / ITR-U under Section 139(8A)
For relevant earlier assessment years, an Updated Return (ITR-U) operates under section 139(8A) of the Income-tax Act, 1961, read with Rule 12AC and the prescribed ITR-U.
The current statutory framework permits an updated return within the prescribed period, presently extending up to 48 months from the end of the relevant assessment year, subject to important eligibility restrictions. The prescribed ITR-U itself reflects this 48-month framework. Etds
But ITR-U is not a general-purpose substitute for FAST-DS.
In particular, section 139(8A) restricts an Updated Return where specified information under laws including the Black Money Act, PMLA and Benami law is already in the Assessing Officer’s possession and has been communicated to the taxpayer.
It also restricts an Updated Return where information for the relevant assessment year has been received under an international agreement referred to in section 90 or section 90A and that information has been communicated to the taxpayer before the ITR-U is furnished. Etds
This restriction is especially relevant in foreign-asset cases because overseas financial information can be received by India through international information-exchange arrangements.
Therefore:
The mere fact that ITR-U exists does not mean it is legally available in every FAST-DS case.
There is another practical distinction.
Where the problem is only an omission in foreign-asset reporting and does not involve additional taxable income, one should not assume that ITR-U is automatically the appropriate mechanism. Its applicability must be tested independently under section 139(8A) and the prescribed return framework.
FAST-DS, in contrast, expressly deals with qualifying foreign assets and foreign income, including specified cases where the underlying income was already taxed or earned while non-resident but the foreign asset was not subsequently reported.
The Protection Is Also Different
A valid FAST-DS declaration followed by the prescribed payment carries specific protection under the Scheme in relation to the foreign income or asset declared.
An ordinary revised return or ITR-U does not merely by being filed confer the same statutory FAST-DS immunity under the Black Money Act.
Accordingly, the three mechanisms should not be treated as interchangeable.
Practical Comparison
| Issue | Revised Return | ITR-U | FAST-DS 2026 |
| Primary purpose | Correct return within normal statutory window | Update eligible earlier income return | Regularise qualifying foreign assets/income |
| Availability | Limited by section 139(5) time limit | Subject to section 139(8A) conditions/restrictions | Subject to sections 130–144 and Scheme conditions |
| Historical Schedule FA issue | Possible only if legally within revised-return window | Must independently satisfy ITR-U provisions | Specifically covers qualifying foreign-asset reporting defaults |
| Foreign income | Can be corrected if revision is available | May be possible subject to eligibility | Specifically covered where Scheme conditions are met |
| Black Money Act immunity | No FAST-DS immunity merely from filing | No FAST-DS immunity merely from filing | Specific immunity for validly declared asset/income |
| FAST-DS deadline | Not applicable | Not applicable | 31 December 2026 |
The correct remedial route should therefore be decided only after examining:
the relevant assessment year, residential status, acquisition history, source of the foreign asset, whether foreign income was taxable in India, previous Schedule FA reporting, information already communicated by the Department, existing proceedings and the statutory limitation periods.
For ordinary return filing and ITR-U matters, see our CA-assisted Income Tax Return Filing Services. The page also contains the current ITR-U framework. CA Alok Kumar
Where the issue specifically concerns historical foreign assets or income, use the separate FAST-DS Filing & Compliance Assistance page.
What Protection Does a Valid FAST-DS Declaration Provide?
The legal significance of FAST-DS lies not merely in filing Form 1 but in the consequences attached to a valid declaration followed by payment.
The official FAST-DS FAQs state that immunity is provided from further tax, penalty and prosecution under the Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015, in respect of the income or asset validly declared.
The declared income or investment in the relevant asset is also not included again in total income in the manner prescribed by the Scheme. FAST-DS-FAQs it
However, this immunity is specific to the income or asset covered by the valid declaration.
FAST-DS should therefore not be presented as a blanket immunity against unrelated income-tax, FEMA, PMLA or other legal issues.
Where proceedings or disputes have already commenced, the interaction with FAST-DS should be examined carefully. Our Income Tax & Black Money Act Litigation Services cover foreign-asset disputes, Schedule FA matters, reassessment and Black Money Act proceedings. CA Alok Kumar
Can FAST-DS Be Used Where Assessment Proceedings Are Pending?
Pending assessment proceedings do not automatically prevent a declaration in every case.
The official FAQs state that where proceedings under the Income-tax Act or Black Money Act are pending in relation to the declared income or asset, the Assessing Officer is required to take the FAST-DS declaration into account while finalising the assessment. FAST-DS-FAQs it
That does not, however, mean that every taxpayer already facing proceedings is eligible.
The specific exclusions and facts of the case must still be checked before Form 1 is filed.
When FAST-DS Is Not Available
The Scheme contains express exclusions.
It does not apply to specified income or assets which directly or indirectly represent proceeds of crime where proceedings have been initiated or are pending under the Prevention of Money-laundering Act, 2002.
The Scheme is also unavailable in respect of income or assets relating to an assessment year for which assessment proceedings have already been completed under the Black Money Act, 2015. FAST-DS-FAQs it
Eligibility should therefore be established before submitting the declaration, not after payment has been made.
Does Everyone Receiving the FAST-DS Advisory Have to Pay ₹1 Lakh?
No.
Receipt of the advisory does not itself create a ₹1 lakh liability.
The ₹1 lakh amount applies only to the specified second category under section 133 and only where the statutory conditions—including the ₹5 crore aggregate ceiling—are satisfied. FAST-DS-FAQs it
A taxpayer whose foreign assets were already correctly disclosed may not require FAST-DS at all.
Does the FAST-DS Email Mean 60% Is Payable?
Again, no.
The effective 60% amount applies to qualifying undisclosed foreign assets and/or undisclosed foreign income under the first statutory route.
An asset whose source is explained and already taxed may fall into a fundamentally different category.
Therefore, “foreign asset”, “undeclared foreign asset” and “undisclosed foreign asset” are not interchangeable expressions.
That distinction should be maintained carefully in all professional advice and documentation.
Can an NRI or RNOR Use FAST-DS?
Potentially, yes.
The Scheme expressly covers certain persons who are presently non-resident or resident but not ordinarily resident (RNOR) but were resident in India in the relevant year when the foreign income arose or when the foreign asset was acquired. FAST-DS-FAQs it
This is especially relevant to returning NRIs who retained:
foreign salary accounts, investments, retirement accounts, insurance policies, shares or other overseas assets after becoming resident in India.
FAST-DS Deadline: Why 31 December 2026 Is Important
The last date for filing FAST-DS Form 1 is:
31 December 2026
The official FAQs clearly state that no declaration can be filed after the last date. FAST-DS-FAQs it
But taxpayers should not treat 31 December as the date to begin reviewing their records.
A proper FAST-DS exercise may require obtaining old foreign bank statements, brokerage statements, RSU/ESOP vesting records, passport and travel history, foreign salary records, overseas tax documents, source-of-funds evidence and valuation reports.
For an account opened many years earlier, reconstructing the Rule 3 deposit history alone can take considerable time.
Frequently Asked Questions – FAQ’s on FAST-DS 2026
Is the FAST-DS advisory email a legal notice?
No. The email itself states that it is an automated advisory for voluntary compliance and not a legal notice. It should nevertheless be reconciled with the taxpayer’s records.
What is the FAST-DS filing deadline?
31 December 2026.
What is the FAST-DS valuation date?
31 March 2026.
What is the FAST-DS ₹1 lakh fee?
It is the prescribed flat fee for the specified foreign-asset reporting-default category, subject to the ₹5 crore aggregate ceiling and the other statutory requirements. FAST-DS-FAQs it
Is FAST-DS tax 60%?
Technically, the first route imposes 30% tax plus an additional amount equal to that tax. The combined financial outgo is therefore effectively 60%. FAST-DS-FAQs it
Can foreign RSUs or ESOPs be covered?
Yes, depending upon the facts. The Government specifically identifies foreign ESOPs and RSUs among the situations in which historical foreign-asset reporting defaults may arise. Etds
Is FAST-DS compulsory merely because I received the email?
No. Eligibility and the existence of an actual disclosure default must first be established.
Is a foreign bank account valued at its closing balance?
Not necessarily. Rule 3 prescribes a deposit-based mechanism subject to specific exclusions. FAST-DS-FAQs it
Can I file ITR-U instead of FAST-DS?
Possibly in some situations, but not automatically. Section 139(8A) contains several eligibility restrictions, including restrictions involving information communicated under specified laws and international information-exchange agreements. Etds
FAST-DS Advisory Received? Reconcile First, File Only After the Position Is Clear
The recent FAST-DS 2026 advisory email should neither cause unnecessary panic nor be ignored.
It signals that the Income Tax Department may possess overseas financial information associated with the taxpayer.
The proper sequence is therefore:
Foreign Assets Information/AIS → residential status → acquisition history → source of funds → taxability of foreign income → earlier ITR and Schedule FA → Rule 3 valuation → FAST-DS eligibility → Form 1 filing.
Three principles are particularly important:
A foreign asset is not automatically an undisclosed foreign asset.
A Schedule FA omission is not automatically undisclosed foreign income.
Receiving a FAST-DS email does not automatically mean that ₹1 lakh or 60% is payable.
Where there is a genuine historical compliance failure, however, the opportunity under FAST-DS is time-bound and the statutory deadline of 31 December 2026 should be taken seriously.
Professional FAST-DS Filing & Compliance Assistance
Taxpayers requiring assistance with the recent Income Tax foreign-assets advisory can obtain professional support for:
FAST-DS eligibility • AIS/Foreign Assets Information reconciliation • residential-status review • Schedule FA analysis • foreign bank-account reconstruction • RSU/ESOP review • source-of-funds analysis • Rule 3 valuation • Form 1 preparation • Form 2 review • ITNS 289 payment guidance • Form 3 filing • Form 4 closure
Visit: FAST-DS 2026 – Foreign Assets Disclosure Scheme Filing & Compliance Assistance
The page also contains independent tools for FAST-DS route identification, eligibility review, amount payable, foreign bank-account valuation and payment timelines. CA Alok Kumar
caalokkumar.com/My-Writing — Empowering with Insights
Leave a Reply