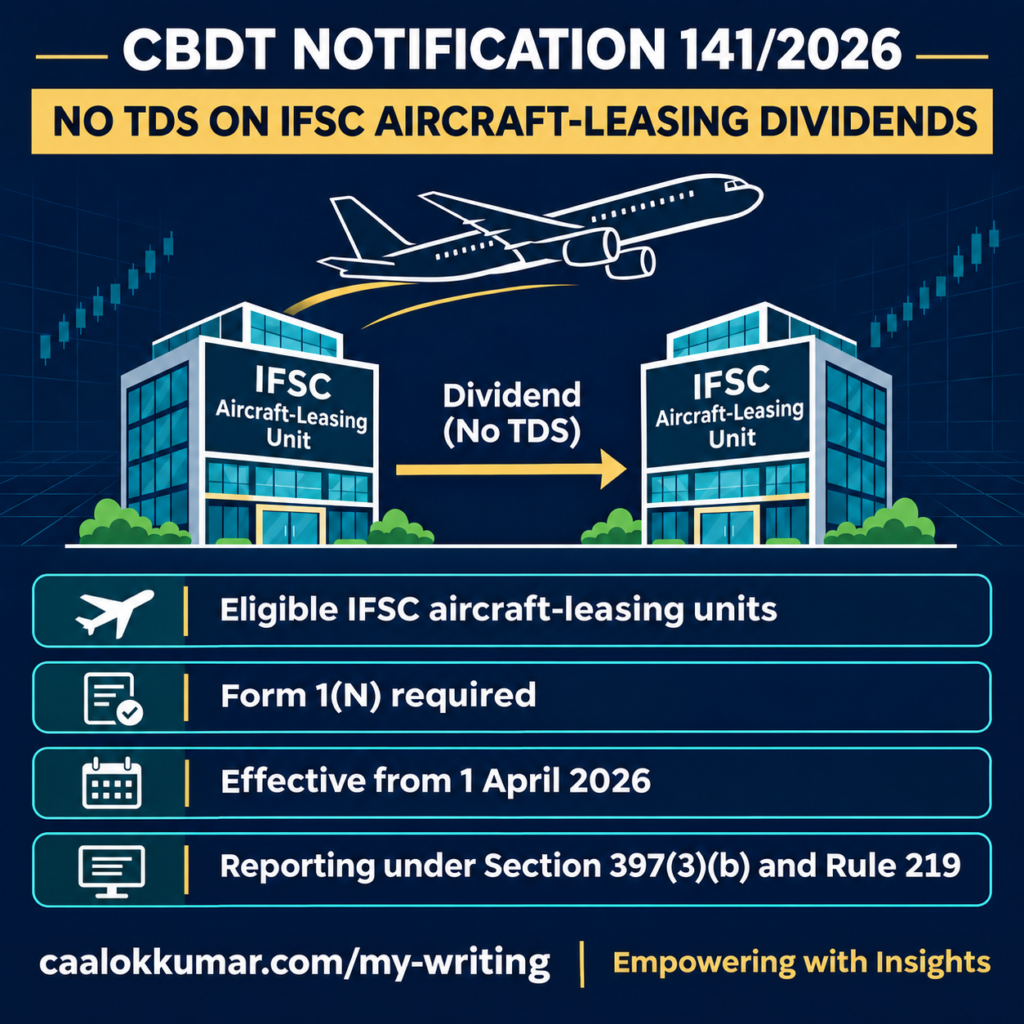
The IFSC aircraft leasing dividend TDS exemption introduced by CBDT provides significant withholding-tax relief to qualifying aircraft-leasing units operating in an International Financial Services Centre.
Through Notification No. 141/2026 dated 4 November 2026, the Central Government has specified that tax need not be deducted from eligible dividend payments made by one qualifying IFSC aircraft-leasing unit to another. The relief is effective retrospectively from 1 April 2026, subject to the prescribed declaration and reporting requirements.
The notification supports efficient movement of funds within eligible IFSC aircraft-leasing structures while ensuring that the benefit is supported by proper documentation.
Notification 141 2026 at a Glance
| Particular | Details |
| Notification | Notification No. 141/2026 |
| Gazette number | S.O. 6016(E) |
| Date | 4 November 2026 |
| Portal publication | 6 November 2026 |
| Effective date | 1 April 2026 |
| TDS provision | Section 393(1), Table S. No. 7 |
| Enabling provision | Section 400(1) |
| Eligible income | Dividend covered by Schedule VI, Table S. No. 11 |
| Declaration | Form No. 1(N) |
| Reporting | Section 397(3)(b) read with Rule 219 |
Major IFSC TDS Relief:What CBDT Has Changed
Under the notification, no tax is required to be deducted under Section 393(1) from an eligible dividend when all specified conditions are satisfied.
- The dividend is paid by an IFSC unit primarily engaged in aircraft leasing.
- The recipient is a company operating as an IFSC unit.
- The recipient company is also primarily engaged in aircraft leasing.
- The dividend income qualifies for exemption under Schedule VI, Table S. No. 11.
- The recipient furnishes Form No. 1(N) to the payer.
- The payer complies with the prescribed TDS-statement reporting requirements.
This is a specific, conditional TDS exemption. It should not be treated as a blanket exemption for every dividend paid by or to an IFSC unit.
Who Can Claim the IFSC Dividend TDS Exemption
The benefit is available only when the prescribed conditions are satisfied by both parties.
Conditions for the Payer
1. Be a unit located in an International Financial Services Centre.
2. Be primarily engaged in the business of leasing aircraft.
3. Receive a duly completed and verified Form No. 1(N) from the payee.
4. Report every qualifying no-TDS dividend payment in the prescribed TDS statement.
Conditions for the Payee
1. Be a company and a unit located in an IFSC.
2. Be primarily engaged in aircraft leasing.
3. Remain an eligible IFSC unit during the relevant tax year.
4. Have dividend income eligible for exemption under Schedule VI, Table S. No. 11.
5. Furnish a tax-year-specific Form No. 1(N) to the payer.
The status of both parties should therefore be verified before the exemption is applied.
What Is Form No 1 N
Form No. 1(N) is a statement-cum-declaration to be furnished by the recipient aircraft-leasing unit to the payer. It requires the following information and confirmations:
- Name and PAN of the payee.
- Name and address of the IFSC unit.
- Contact number and email address.
- Relevant tax year.
- Declaration that the unit is engaged in aircraft leasing.
- Confirmation that the dividend is eligible under Schedule VI, Table S. No. 11.
- Confirmation that the unit continues to operate in the IFSC and remains engaged in aircraft leasing during the relevant tax year.
The form must be signed by a person competent to sign the return of income under Section 265 of the Income-tax Act, 2025.
When the Payer Can Stop Deducting TDS
The notification states that the payer shall not deduct tax on a dividend paid or credited after the date on which Form No. 1(N) is received from the payee. This timing condition is important.
The payer should not rely solely on the recipient’s verbal confirmation or IFSC registration. A properly completed Form No. 1(N) should be obtained before applying the no-TDS treatment.
A prudent compliance file should contain:
- Form No. 1(N).
- Proof of the date on which the form was received.
- IFSC-unit registration documents.
- Evidence that the payer and payee are primarily engaged in aircraft leasing.
- Eligibility analysis under Schedule VI.
- Dividend declaration and payment documents.
- Details reported in the relevant TDS statement.
Reporting Remains Mandatory Despite No TDS
The exemption from deduction does not eliminate the payer’s reporting responsibility. The payer must furnish particulars of all qualifying dividend payments on which tax was not deducted in the statement prescribed under Section 397(3)(b), read with Rule 219 of the Income-tax Rules, 2026.
Finance and tax teams should configure their systems to identify qualifying dividends, the date of receipt of Form No. 1(N), the payment or credit date, the dividend amount, the recipient’s PAN and IFSC-unit details, and the amount reported as a no-TDS payment.
Retrospective Effect from 1 April 2026
Notification No. 141/2026 is deemed to have come into force on 1 April 2026, even though it was issued on 4 November 2026. Eligible entities should review dividend payments or credits made from 1 April 2026 up to the notification date.
- Whether both units met the prescribed eligibility conditions.
- Whether Form No. 1(N) was available or can validly support the relevant transaction.
- Whether TDS was already deducted and deposited.
- Whether the transaction was reported in the applicable TDS statement.
- Whether any correction statement, tax credit or refund-related action is required.
Where tax has already been deducted and deposited, the payer should not reverse or refund it informally. The appropriate correction, credit or refund procedure should be examined based on the transaction records and applicable portal functionality.
Why the Relief Matters for IFSC Aircraft Leasing
Aircraft leasing normally involves capital-intensive group structures, special-purpose entities and periodic distributions of profits. Withholding tax on eligible intra-IFSC dividends can restrict working capital until the recipient obtains corresponding tax credit or refund.
- Improved cash-flow efficiency.
- Reduced temporary blockage of funds through TDS.
- Simplified intra-group dividend distribution.
- Greater certainty for qualifying IFSC leasing structures.
- Improved competitiveness of India’s aircraft-leasing ecosystem.
These advantages depend upon accurate eligibility analysis and timely documentation.
Form 1 N Does Not Replace Foreign Remittance Compliance
Form No. 1(N) is confined to eligible dividend payments between qualifying IFSC aircraft-leasing units. It does not replace the compliance applicable to other payments made to non-residents or foreign entities.
If an IFSC or aircraft-leasing company subsequently makes a royalty, interest, service-fee, lease-rental or other cross-border payment, a separate taxability and withholding review may be required.
Businesses undertaking such transactions may refer to the detailed guidance on Form 145 and Form 146 foreign-remittance compliance.
Entities requiring transaction-specific assistance in Delhi NCR can also review the available CA certificate for foreign remittance in Delhi services.
- Form 1(N) supports the specified IFSC dividend no-TDS treatment.
- Form 145 and Form 146 may apply to prescribed foreign-remittance reporting and certification.
- One form should not be treated as a substitute for the other.
Practical Action Plan
For the Recipient Company
- Confirm eligibility under Schedule VI, Table S. No. 11.
- Complete Form No. 1(N) for the relevant tax year.
- Ensure that the form is signed by an authorised person.
- Furnish the form before the dividend is paid or credited.
- Retain evidence establishing continued IFSC and aircraft-leasing status.
- Notify the payer immediately if eligibility changes during the tax year.
For the Payer
- Verify the recipient’s status as an eligible IFSC aircraft-leasing company.
- Record the date on which Form No. 1(N) is received.
- Apply the no-TDS treatment only to payments or credits made after receipt of the form.
- Preserve the declaration and supporting documents.
- Report the payment under Section 397(3)(b) read with Rule 219.
- Review payments already made from 1 April 2026 onwards.
Frequently Asked Questions
Does Notification 141/2026 exempt every IFSC dividend from TDS?
No. It applies only to eligible dividends paid between specified IFSC units primarily engaged in aircraft leasing. The recipient must be a company and satisfy the Schedule VI eligibility conditions.
Is Form No. 1(N) mandatory?
Yes. The recipient must furnish the prescribed statement-cum-declaration to the payer for the relevant tax year.
Can the payer stop deducting TDS before receiving Form No. 1(N)?
The notification provides no-TDS treatment for a payment or credit made after the payer receives the form. Obtaining the form before applying the exemption is therefore essential.
From which date is the relief available?
The notification is deemed effective from 1 April 2026.
Must the payer report the payment even when no tax is deducted?
Yes. The qualifying no-TDS dividend payment must be reported under Section 397(3)(b), read with Rule 219.
Does Form No. 1(N) replace Forms 145 and 146?
No. Form No. 1(N) applies to the specified IFSC dividend exemption, while Forms 145 and 146 concern prescribed foreign-remittance compliance and certification.
Conclusion
CBDT Notification No. 141/2026 is an important step towards improving the tax efficiency of India’s IFSC aircraft-leasing sector. It removes TDS from eligible dividend payments between qualifying aircraft-leasing units, but the relief is documentation-driven.
The key compliance requirements are clear: verify eligibility, obtain Form No. 1(N) before applying the exemption, preserve supporting evidence and report every no-TDS payment in the prescribed TDS statement. Eligible IFSC units should also review transactions undertaken from 1 April 2026 because the notification operates retrospectively.
Official References
Disclaimer
This article is intended for general informational purposes and does not constitute legal, tax, investment or professional advice. Eligibility for the exemption depends on the facts of each transaction, the status of the payer and payee, compliance with Schedule VI and timely furnishing of Form No. 1(N). Professional advice should be obtained before applying the no-TDS treatment or revising earlier compliance.
Suggested hashtags: #CBDT #Notification1412026 #IFSC #AircraftLeasing #DividendTDS #TDSExemption #Form1N #GIFTCity #IncomeTaxAct2025 #TaxCompliance #InternationalTax #AviationFinance
Leave a Reply