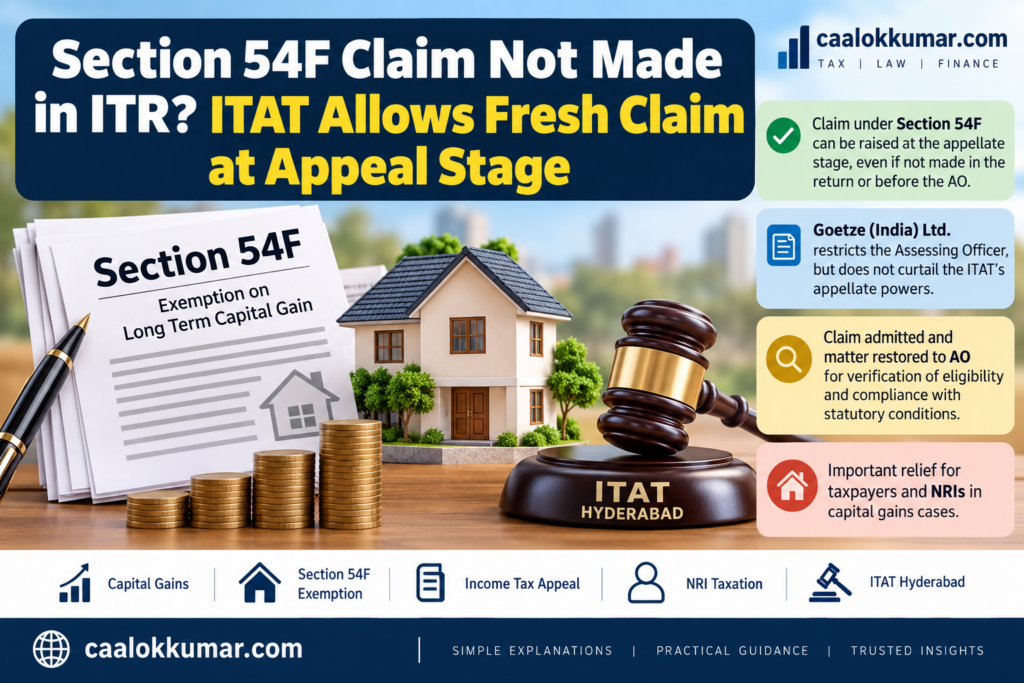
Section 54F Claim Can Be Raised at Appellate Stage Even If Not Claimed in ITR: ITAT Hyderabad
Can a Section 54F claim not made in ITR still be claimed during income-tax appellate proceedings?
In an important ruling for taxpayers facing capital gains disputes, the Hyderabad Bench of the Income Tax Appellate Tribunal has held that a claim for Section 54F exemption can be admitted at the appellate stage even where the deduction was neither claimed in the return of income nor before the Assessing Officer.
In Shri Kiran Kumar Grandhe, Hyderabad v. Income Tax Officer (International Taxation)-1, Hyderabad, ITA No. 1068/Hyd/2026, order dated 23 September 2026, the ITAT clarified an important distinction arising from the Supreme Court decision in Goetze (India) Ltd. v. CIT.
The restriction laid down in Goetze (India) applies to the Assessing Officer’s ability to entertain a fresh claim outside a revised return. It does not curtail the appellate powers of the ITAT under Section 254.
However, the Hyderabad ITAT did not automatically grant the Section 54F deduction. It admitted the fresh claim and restored the matter to the Assessing Officer for verification of the taxpayer’s eligibility and compliance with all statutory conditions.
The ruling is particularly relevant for taxpayers and NRIs who have omitted a legitimate capital gains exemption from their ITR or where an alternative exemption becomes relevant only during assessment or appellate proceedings.
Case Details: Kiran Kumar Grandhe v. ITO
Case: Shri Kiran Kumar Grandhe, Hyderabad v. Income Tax Officer (International Taxation)-1, Hyderabad
Appeal: ITA No. 1068/Hyd/2026
Assessment Year: 2020-21
Forum: Income Tax Appellate Tribunal, Hyderabad
Order Date: 23 September 2026
Relevant Provisions: Sections 54F, 147, 148, 144C and 254 of the Income-tax Act, 1961
The principal issue before the Tribunal was whether a Section 54F claim at the appellate stage could be entertained when no such claim had been made in the return filed pursuant to Section 148 or before the Assessing Officer.
What Was the Section 54F Dispute?
The assessee was a non-resident individual who had not originally filed a return for Assessment Year 2020-21 under Section 139.
Based on information relating to transfer of immovable property, reassessment proceedings were initiated under Section 147 and notice under Section 148 was issued.
The assessee thereafter filed a return declaring total income of ₹3,130.
During reassessment, the Assessing Officer initially proposed an addition of approximately ₹1 crore as short-term capital gain.
The assessee challenged the proposed assessment before the Dispute Resolution Panel.
The DRP ultimately concluded that the gain was long-term capital gain and determined it at ₹49,25,389, instead of the ₹1 crore short-term capital gain initially proposed by the AO.
For taxpayers dealing with property or investment transactions, correct identification and computation of LTCG/STCG is crucial. Our capital gain tax calculator may be used for a preliminary understanding of capital gains computation, while the final tax position should always be based on the applicable law and supporting documents.
Section 54F Exemption Was Not Claimed in the Return
The difficulty arose because the assessee had not claimed deduction under Section 54F:
- in the return filed in response to notice under Section 148; or
- before the Assessing Officer.
The Section 54F claim was subsequently raised before the DRP.
The DRP rejected the claim at the threshold primarily because the exemption had not been claimed in the return of income.
Consequently, the taxpayer’s factual eligibility for the exemption was never examined on merits.
This ultimately resulted in the question reaching the ITAT:
Can Section 54F be claimed if it was not claimed in the ITR?
The Hyderabad ITAT held that, in appropriate circumstances, the Tribunal can entertain such an additional statutory claim.
What Is Section 54F Exemption?
Section 54F of the Income-tax Act provides exemption from long-term capital gains to an individual or HUF where capital gain arises from transfer of a long-term capital asset other than a residential house and the prescribed conditions relating to investment in a residential house in India are fulfilled.
Broadly, the taxpayer must purchase the qualifying residential house:
- within one year before the transfer; or
- within two years after the transfer;
or construct the residential house within three years after the transfer.
The exemption is also subject to several other statutory conditions relating to ownership of residential houses, quantum of investment, transfer of the new house and utilisation/deposit of the consideration.
Taxpayers considering residential reinvestment may also read our analysis of Section 54 exemption for residential housesto understand how capital-gains exemptions are examined in property transactions.
Goetze (India): Why the AO and ITAT Have Different Powers
The Revenue’s objection centred on the Supreme Court judgment in:
Goetze (India) Ltd. v. CIT (2006) 284 ITR 323 (SC)
In Goetze (India), the Supreme Court held that an Assessing Officer could not entertain a fresh deduction claim otherwise than through a revised return.
But an extremely important clarification was made in the same judgment.
The Supreme Court specifically stated that the decision did not impinge upon the powers of the Income Tax Appellate Tribunal.
Therefore, Goetze (India) should not be read as laying down an absolute prohibition against every fresh claim not made in the return of income.
The practical distinction is:
Before the Assessing Officer:
A fresh claim outside the return or revised return may face the restriction laid down in Goetze (India).
Before appellate authorities:
The appellate authority’s jurisdiction is wider, and the Tribunal may consider an additional legal claim in appropriate circumstances.
This distinction can become extremely important in tax litigation and ITAT appeals, particularly where an exemption, deduction or alternative legal claim was omitted from the original return or becomes relevant because of findings made during assessment.
Jute Corporation: Additional Claims Can Be Considered in Appeal
The Tribunal also relied upon the Supreme Court ruling in:
Jute Corporation of India Ltd. v. CIT (1991) 187 ITR 688 (SC).
The Supreme Court recognised the power of the appellate authority to entertain an additional ground in an appropriate case even if it had not been raised before the Assessing Officer.
Therefore, appellate proceedings are not necessarily restricted only to claims expressly made in the original return.
This principle assumes considerable importance where a taxpayer has a legitimate statutory entitlement but fails to claim it at the initial stage.
Why Did the ITAT Admit the Fresh Section 54F Claim?
The facts of the case were significant.
Initially, the assessee was disputing the very taxability of the capital gain in the relevant assessment year.
From the taxpayer’s standpoint, therefore, there was no occasion at that stage to make an alternative Section 54F claim.
Once the authorities finally concluded that long-term capital gain was taxable in Assessment Year 2020-21, the alternative claim for Section 54F deduction became relevant.
The ITAT considered the explanation reasonable.
Accordingly, failure to claim Section 54F at the earlier stage could not, by itself, prevent the taxpayer from raising the alternative statutory claim before the Tribunal.
Admission of Section 54F Claim Is Not Automatic Allowance
This is the most important qualification in the judgment.
The ITAT did not hold that the assessee automatically became entitled to Section 54F exemption.
It distinguished between:
admitting the claim, and
allowing the exemption after verification.
The DRP had rejected the claim without examining the taxpayer’s factual eligibility.
Therefore, the ITAT considered verification by the Assessing Officer necessary.
Matter Restored to the Assessing Officer
The Tribunal restored the Section 54F issue to the AO with directions to:
- examine the taxpayer’s eligibility under Section 54F;
- verify compliance with all statutory requirements;
- examine supporting documents;
- provide adequate opportunity of hearing; and
- allow the deduction to the extent admissible under law.
The taxpayer was permitted to furnish all necessary evidence and explanations.
Therefore, this ruling should be cited as an authority supporting the admission of a Section 54F claim not made in the return, rather than as a judgment granting an unconditional Section 54F exemption.
What Documents Should Support a Section 54F Claim?
A taxpayer claiming Section 54F should normally maintain:
- Sale deed of the original capital asset;
- Purchase deed and cost documents of the original asset;
- Long-term capital gain computation;
- Agreement and purchase deed of the new residential house;
- Construction agreement and invoices, where applicable;
- Bank statements and payment trail;
- Possession and registration documents;
- Capital Gains Account Scheme deposit proof, wherever applicable;
- Details of residential houses already owned on the relevant date;
- Evidence establishing the date of purchase or construction; and
- Correct Schedule CG disclosure in the income-tax return.
Correct reporting becomes particularly important while undertaking income tax return filing involving property transactions, shares, mutual funds and other capital assets.
Why the Judgment Is Important for Taxpayers
The Hyderabad ITAT decision reinforces several important principles.
1. Omission from ITR May Not End a Legitimate Claim
A genuine statutory exemption does not necessarily become permanently unavailable merely because it was omitted from the original return.
The appropriate remedy will, however, depend upon the stage of proceedings and the facts of the case.
2. Goetze Restricts the AO, Not the ITAT
The restriction identified by the Supreme Court in Goetze (India) relates to entertaining a fresh claim by the Assessing Officer without a revised return.
It does not extinguish the Tribunal’s appellate jurisdiction.
3. Alternative Claims Can Become Relevant During Litigation
A taxpayer may primarily argue that a particular receipt or capital gain is not taxable.
An alternative claim for exemption or deduction may become relevant only if that primary contention is rejected.
This case demonstrates why alternative grounds should be carefully evaluated during income tax appeal and tax litigation.
4. Admission Does Not Mean Automatic Tax Relief
Even where the Tribunal admits an additional claim, the taxpayer must still satisfy every statutory requirement for receiving the deduction.
Documentation therefore remains crucial.
Special Relevance of Section 54F for NRIs
The assessee in this case was a non-resident individual.
The ruling is therefore particularly relevant for NRI taxation and property transactions in India.
NRIs frequently encounter capital-gains issues involving:
- sale of immovable property;
- long-term capital gain computation;
- Section 54 or Section 54F exemption;
- TDS under Section 195;
- lower deduction certificates;
- property valuation;
- reassessment proceedings;
- repatriation of sale proceeds; and
- documentation required by banks and tax authorities.
NRIs dealing with Indian property transactions can refer to our dedicated NRI taxation and property sale advisory for the tax, TDS, FEMA and compliance aspects of such transactions.
Section 54F Under the Income-tax Act, 2025
Tax professionals and taxpayers should also note that statutory section numbering has changed under the Income-tax Act, 2025.
Section 54F of the Income-tax Act, 1961 broadly corresponds to Section 86 of the Income-tax Act, 2025.
For comparison of old and new section numbers, taxpayers and professionals may use our Income Tax Act 2025 Section Finder.
The assessment year involved in the present dispute must, however, be analysed under the statutory provisions applicable to that year.
What If Section 54F Has Already Been Disallowed?
Where the AO has rejected or failed to consider a legitimate capital-gains exemption, the assessment order should be examined promptly.
Depending upon the facts, available remedies may include:
- rectification;
- appeal before CIT(A)/NFAC;
- additional grounds before the appellate authority;
- ITAT appeal;
- stay of demand; or
- appropriate consequential proceedings.
Where an assessment results in an outstanding demand, taxpayers should also examine the available options for income tax demand notice response, stay and appeal within the applicable limitation period.
Can Every Fresh Deduction Be Claimed Before ITAT?
No.
This judgment should not be interpreted as an automatic right to introduce any claim at any stage.
Relevant considerations may include:
- nature of the claim;
- reason for not claiming it earlier;
- material already available on record;
- whether further factual verification is necessary;
- statutory conditions governing the exemption;
- applicable jurisdictional High Court decisions; and
- exercise of appellate discretion.
The Hyderabad ITAT itself considered the particular facts and the explanation offered by the assessee before admitting the Section 54F claim.
Final Outcome of Kiran Kumar Grandhe Case
The ITAT:
- admitted the additional Section 54F claim;
- restored the issue to the Assessing Officer;
- directed the AO to verify statutory eligibility;
- permitted the assessee to furnish supporting evidence;
- directed that adequate opportunity of hearing be provided; and
- ordered the deduction to be allowed to the extent admissible under law.
The appeal was accordingly allowed for statistical purposes.
The other grounds, including the challenge to reassessment, were kept open since the assessee agreed not to press them at that stage if the Section 54F claim was admitted for consideration.
Key Takeaway: Section 54F Claim Not Made in Return May Still Be Considered
The Hyderabad ITAT ruling in Kiran Kumar Grandhe v. ITO (International Taxation) provides important guidance where a taxpayer has a genuine Section 54F claim not made in the return of income.
The ruling confirms that the decision in Goetze (India) Ltd. does not prevent the ITAT from exercising its appellate jurisdiction to entertain an additional statutory claim.
A taxpayer’s failure to claim an exemption in the ITR therefore does not necessarily end the matter once the dispute reaches an appellate authority.
However, admission of the claim and entitlement to the exemption are two separate issues.
The taxpayer must still establish complete compliance with Section 54F through proper documents and evidence.
For taxpayers dealing with property sales, capital gains, reassessment or appellate proceedings, careful review of the assessment order, available exemptions and alternative grounds can prevent a legitimate statutory benefit from being lost merely because it was not originally claimed.
FAQs on Section 54F Claim Not Made in Return
Can Section 54F be claimed if it was not claimed in the ITR?
The Hyderabad ITAT has held that an additional Section 54F claim can be entertained at the appellate stage even where it was not claimed in the return or before the AO, subject to the facts and verification of statutory eligibility.
Does Goetze (India) prevent a fresh claim before ITAT?
No. The Supreme Court expressly clarified in Goetze (India) Ltd. v. CIT that its ruling concerning a fresh claim before the AO did not impinge upon the powers of the ITAT.
Can a fresh deduction be claimed before the ITAT?
An additional statutory claim may be entertained by the Tribunal in appropriate circumstances. The power is not the same as an automatic entitlement to the deduction; factual and statutory eligibility must still be proved.
Did Hyderabad ITAT actually allow Section 54F exemption?
The Tribunal admitted the claim but did not finally allow the exemption itself. It restored the matter to the AO for verification and directed the exemption to be allowed to the extent legally admissible.
Can an NRI claim Section 54F exemption?
Yes. An NRI who is an individual can claim Section 54F subject to fulfilment of all applicable conditions. Residential status by itself does not bar the exemption.
What should a taxpayer do if Section 54F was omitted from the ITR?
The appropriate course depends upon whether the return can still be revised, whether assessment proceedings are pending, whether an assessment order has already been passed and whether appellate proceedings are underway. The available procedural remedy should therefore be examined before making the claim.
What is Section 54F under the Income-tax Act, 2025?
Section 54F of the Income-tax Act, 1961 broadly corresponds to Section 86 of the Income-tax Act, 2025.
Cases relied upon:
Goetze (India) Ltd. v. CIT (2006) 284 ITR 323 (SC)
Jute Corporation of India Ltd. v. CIT (1991) 187 ITR 688 (SC)
Disclaimer: This article is intended for general information and professional discussion. Eligibility for Section 54F exemption and the ability to raise an additional claim depend upon the applicable assessment year, facts, evidence, statutory provisions and judicial precedents. Professional advice should be obtained before taking any tax or appellate position.
income tax demand notice response https://caalokkumar.com/income-tax-demand-notice-response.html
Leave a Reply